by Leo Pareja | Aug 23, 2024 | Industry, News Feed
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
The U.S. luxury real estate market has made a stronger showing during the first half of 2024 than it did in the first half of 2023, according to midyear luxury reports from Coldwell Banker, Compass and Sotheby’s International Realty.
The number of ultra-luxury homes (those $10 million and higher) that sold during the first half of the year increased by 3.9 percent from the first half of 2023, according to Compass’ report.
TAKE THE INMAN INTEL INDEX SURVEY FOR AUGUST
Sales of single-family properties across the full spectrum of the luxury market (defined as the top 10 percent of the market) were up 2.66 percent year over year, according to Coldwell Banker’s report, while attached luxury sales only increased by 0.25 percent year over year.
Luxury prices also hit new heights, with the median price for the top 10 percent of U.S. luxury homes up 37.5 percent as of June 2024 from June 2020 levels to $1.695 million, according to Coldwell Banker.
“Premium properties remain timeless, and the findings of this report demonstrate a strong commitment from both buyers and sellers to complete transactions,” Felipe Hernandez Smith, head of Compass Luxury, said in a statement. “There are exceptional homes nationwide catering to every lifestyle, and it’s encouraging to see that premium real estate is always in vogue.”
Overall, luxury agents and brokers are optimistic about how 2024 has shaped up thus far and where it seems to be heading, with nearly 70 percent of Coldwell Banker Global Luxury property specialists expressing optimism in this year’s market. A few key factors agents will keep an eye on as the year continues, as brokerage midyear luxury reports suggest, include dream homebuying trends, elections, the economy, and growing and emerging markets.
Consumer trends: unicorns and dream homes
Desirable inventory continues to drive market demand, particularly those homes that don’t require any work before moving in, Coldwell Banker’s report noted.
More than 44 percent of the firm’s luxury specialists said that well-priced, well-presented homes, especially those that are “unicorns,” meaning move-in ready, brand-new or with many amenities, continue to see high demand.
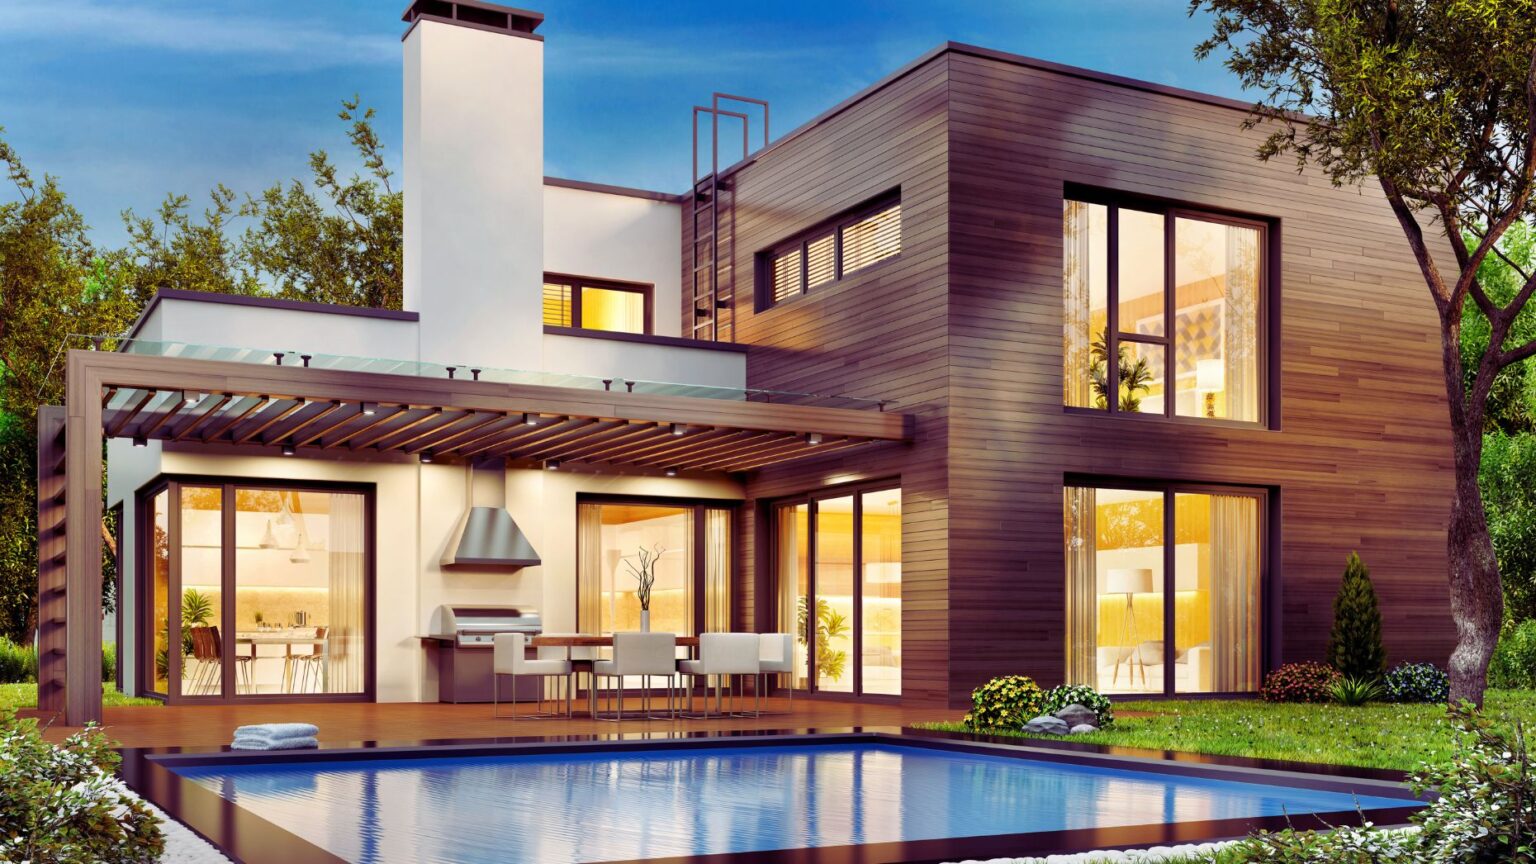
“Demand for luxury spec houses and townhomes remains particularly strong,” Coldwell Banker’s report said. “Modern aesthetics with natural materials like wood, an open plan, eco-friendly features and the latest smart home technology — these are all on the must-have list, along with flexible and functional living spaces that cater to a variety of experience, wellness and a sense of community. This shift seems to be driven by growing numbers of younger affluent buyers who have different priorities than previous generations.”
A growing number of luxury homebuyers today are also seeking out their forever dream home, Coldwell Banker luxury agents said. During the pandemic, clients scrambled for a place in which to shelter, but now that their lives have normalized and many remote work policies are shifting, agents said that buyers are looking for new homes that match their long-term goals. Life transitions, like starting a family, are also increasingly a source of motivation for buyers who are moving, agents added.
Credit: Canva
Elections
Time Magazine has called 2024 “the ultimate election year” for a reason — about half of the world’s voting-age population, or more than four billion people across 80 countries, will be eligible to vote in elections this year. How things shake out in the polls in the U.S. could have a significant impact on the real estate market, Sotheby’s midyear report noted.
Democrat and Republican platforms are also moving in different directions when it comes to real estate — Democrats are targeting housing affordability through initiatives like tax credits and down-payment assistance, while Republicans are hoping to stimulate economic growth through pro-business policies, like low taxes and low regulations.
Seasoned agents know that buyers and sellers tend to take a break from the market during elections.
“From my experience, what we see again and again is that our market gets quieter around October,” in anticipation of the election in November, Christie-Anne Weiss with TTR Sotheby’s International Realty in Washington, D.C., said in the firm’s report. “Once the election is over and we know who the president is, business will resume as normal. It is buyer psychology; people do not make major investment decisions when there is imminent uncertainty.”
The same holds true for other countries across the globe, international agents affiliated with Sotheby’s International Realty suggested. But political stability can also have a positive impact on the market.
Since India’s incumbent Bharatiya Janata Party retained power in this year’s elections, India Sotheby’s International Realty’s Ashwin Chadha expects the real estate market to benefit.
“The current government has reiterated its intentions for high spending, drawing in investments to boost the manufacturing section,” Chadha said. “Both infrastructure spending and manufacturing augur positively for the property market, including luxury real estate.”
Economic factors
The political landscape will undoubtedly have some kind of impact on the market, but interest rate movements may impact buyers and sellers even more, Sotheby’s luxury specialists said.
“There’s a lot more conversation about politics this year and a lot of polarization,” Russ Anderson, president and CEO of Briggs Freeman Sotheby’s International Realty in Dallas said. “But, when it comes to real estate, people are more focused on interest rates than politics. No matter who wins, if interest rates start falling, I think people will buy. If they stay elevated, people will remain on the sidelines.”
The expected drop in interest rates has not come as quickly as consumers and real estate agents might have hoped. Now, economists are estimating that rate drops will come by 2025. The Mortgage Bankers Association (MBA) anticipates that rates will fall to about 5.9 percent by 2025 and Wells Fargo estimated that they would drop to 6 percent.
“I believe we can say with some certainty that U.S. mortgage rates will be lower at the end of the year,” Anthony Chan, former chief economist of JPMorgan Chase, said in Sotheby’s International Realty’s report. “As buyers see lower rates, they will be less worried about the ‘lock-in effect’ — the hesitancy of selling their house if it means taking out a higher-rate mortgage for their next home. This will ultimately support housing activity if the economy avoids a slowdown.”
In addition to interest rates, rising prices and low inventory also continue to present challenges to homebuyers. Until inventory hits normal levels of about six months, prices will continue to experience upward pressure. Experts from Goldman Sachs told Sotheby’s International Realty that home prices could increase by 5 percent in 2024 and by 3.7 percent in 2025.
Luxury buyers may be more concerned with U.S. equity markets than interest rates, however, Sotheby’s International Realty’s report noted. “If investors are doing well, as they did in 2023 and have so far in 2024, that will boost demand for luxury housing,” Anthony Chan added.
Changes in U.S. interest rates will also ultimately have an indirect and somewhat delayed impact on the economies of other countries throughout the globe.
“Some estimates suggest that it takes between one and two years for U.S. monetary policy to have its maximum effect,” Julian Brown of New Zealand Sotheby’s International Realty said. “However, there is a large degree of uncertainty because the structure of the economy changes over time, and conditions vary.”
Nashville has seen a surge in ultra-luxury sales so far this year | Canva
Market highlights
Los Angeles saw the greatest number of $10 million-plus transactions during the first half of the year with 135 sales accounting for $2.67 billion in sales volume, according to Compass’ midyear ultra-luxury report. Manhattan, Palm Beach County, Miami-Dade and Orange County rounded out the top five markets with the most ultra-luxury sales.
The number of ultra-luxury sales rose year over year in 20 markets, including Florida markets in Palm Beach, Miami-Dade and Orange County, as some buyers used these investments as a means to hedge against inflation, and often relied on their cash-buying power to acquire properties to circumnavigate high mortgage rates.
Emerging markets and second-home markets, especially those with tax-favorable policies, saw the greatest growth during the first half of the year, Compass reported, with the greater Nashville region seeing a 600 percent annual increase in ultra-luxury sales with a total of seven ultra-luxury sales, and Central Jersey seeing a 500 percent increase in such sales with a total of six ultra-luxury sales.
Out of those markets with 10 or more $10-million-plus sales during the first half of the year, Orange County, Telluride and Greater Palm Springs saw the greatest annual increase in ultra-luxury sales.
“With an increased supply of luxury listings, our sales would undoubtedly climb even higher,” Valery Neuman, a Compass Palm Springs agent, said. “Looking ahead, the second half of the year holds great promise as more people discover the allure of Palm Springs.”
Get Inman’s Luxury Lens Newsletter delivered right to your inbox. A weekly deep dive into the biggest news in the world of high-end real estate delivered every Friday. Click here to subscribe.
Email Lillian Dickerson
by Lillian Dickerson | Aug 23, 2024 | Industry, News Feed
This report was originally published on July 29, 2024, exclusively for subscribers of Intel, the data and research arm of Inman. Subscribe to Inman Intel for a deeper analysis of the business of real estate.
More U.S. adults have become open to buying a home in the coming months, and the factors driving active shoppers amid this depressed market are more varied than is often assumed, a new Intel survey finds.
- The share of working U.S. adults who said they were at least somewhat likely to buy a home in the next 12 months inched up by 3 percentage points from April to July, according to the Inman-Dig Insights consumer survey.
- The share of adults who said they were actively shopping for homes also rose over the past three months — although this likely reflects seasonal activity in the heat of the summer market, when housing demand is near its peak.
The Inman-Dig Insights consumer survey ran in early July and received responses from 3,000 adults with full-time or part-time jobs. Its results shed light on how potential real estate clients — both in the present and near-future — are thinking about the home market.
The survey also produced a host of detailed insights into consumer attitudes, including:
- What drove today’s active homebuyers to the market
- What non-buyers say will pull them into the market in the months ahead
- How renters and homeowners are viewing the landscape in their own unique ways
Read the full findings in the report below.
More than just ‘forced to move’
Even in times of poor affordability, major life changes help prop up home transactions: events like job change, marriage, having kids, death or divorce.
And that’s part of the picture for sure.
But real estate professionals — and now, homebuyers themselves — will also tell you it’s more complex than that.
Active homebuyers tell the Inman-Dig Insights consumer survey that they are motivated by a host of factors — including, surprisingly, the desire to find a larger or nicer home even in this high-rate environment.
Share of active homebuyers in early July who said their decision to buy is motivated in part by…
- 32% — Seeking larger or nicer house
- 31% — Job-related relocation
- 29% — Financial benefits of homeownership
- 25% — Moving closer to family
- 17% — Getting married
- 17% — Planning to retire
- 15% — Having a child
- 15% — Seeking second home or investment property
- 15% — Seeking smaller or more affordable house
- 11% — Seeking better school district
- 8% — Getting divorced
- 7% — Children moving out of the home
The desire to upgrade one’s home often goes underdiscussed in real estate circles these days, but this survey demonstrates that it remains one of the top factors driving consumers to the home market.
That share of consumers may still be lower today than it was when mortgages were cheaper and homes more affordable. But because July was the first time the survey asked this question, Intel is not in a position say how that share had changed over time.
That said, the active buyers who said they were seeking a larger or nicer house did give some clues as to their thinking. Buyers seeking a home upgrade were less likely to say they were moving for family-related reasons, and more likely to say that a job change, a better school district or plans to retire were driving their decision to buy now.
Intel also identified that significantly different factors are driving homeowners and buyers to the market.
Today’s homeowners actively shopping for homes are more likely than renters to be driven by:
- Job-related relocation — 36%
- Seeking second home or investment property — 22%
- Moving closer to family — 29%
- Planning to retire — 19%
Today’s renters actively shopping for homes are more likely than homeowners to be driven by:
- Getting married — 22%
- Seeking a better school district — 15%
- Seeking a larger or nicer home — 35%
- Financial benefits of homeownership — 31%
These results represent the current pool of buyers that real estate agents were working with day-in and day-out in early July.
But Intel also sought the opinions of buyers who are not yet on the market, but expect to enter it sometime soon.
The next wave of buyers
The next 12 months are likely to bring more buyers into the fold — but they’re likely to be even more sensitive to affordability than the clients of today have been.
They’re also less likely to be investors, and less likely to expect to have to move as a result of a change in their employment.
- Only 20 percent of near-term future buyers say that they expect they’ll be driven by a job-related relocation. That’s compared to 31 percent of today’s buyers who say a job change is driving them to move. This may be largely driven by the fact that job changes can be difficult to predict in advance.
- A mere 9 percent of future buyers say they’ll be seeking a second home or investment property, compared to 15 percent of today’s buyers who say the same.
Instead, the next wave of homebuyers are especially likely to say they’ll be motivated by a desire to downsize.
- 19 percent of near-future buyers say they’ll look at downsizing or lowering their monthly housing costs when they hit the market, compared to 15 percent of buyers today.
- 11 percent of future buyers say that they’re planning to move because children are moving out of the home, compared to 7 percent of active buyers.
Certain tendencies also stood out among homeowners and renters who were likely to buy a home in the next 12 months.
Today’s homeowners who are not actively shopping, but expect to buy in the coming year, are more likely to be driven by:
- Planning to retire — 21%
- Getting divorced — 11%
- Children moving out of the home — 12%
Today’s renters who are not actively shopping, but expect to buy in the coming year, are more likely to be driven by:
- Financial benefits of homeownership — 36%
- Seeking a larger or nicer home — 38%
- Seeking a smaller or more affordable home — 20%
It’s notable that renters can be driven one of two ways, depending on their situation: Many are seeking a larger or nicer place than their current rental unit, as expected.
But we also see signs that renters care more about affordability than other groups. As such, some consumers renting a house may be looking to move into a smaller place when they purchase.
The renters who plan to buy in the next 12 months are more likely to say they’re driven by the financial benefits of homeownership than renters who are shopping for homes today. In today’s challenging affordability environment, it’s possible that active shoppers are a bit less enthusiastic that their home purchase will be a sound financial investment.
About the Inman-Dig Insights Consumer Survey
The Inman-Dig Insights consumer survey was conducted from July 5 through July 7 to gauge the opinions and behaviors of Americans related to homebuying.
The survey sampled a diverse group of 3,000 American adults, ranging in age from 24 to 65 and employed either full-time or part-time. The participants were selected to produce a broadly representative breakdown by age, gender and region.
Statistical rigor was maintained throughout the study, and the results should be largely representative of attitudes held by U.S. adults with full- or part-time jobs. Both Inman and Dig Insights are majority-owned by Toronto-based Beringer Capital.
Email Daniel Houston
by Justin Ziegler | Aug 23, 2024 | Industry, News Feed
Compass agents have united to launch BDG Partners, a full-service team based in Nashville, Tennessee, with the addition of real estate veteran Grant Hammond, the firm announced.
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
Compass agents have united to launch BDG Partners, a leading luxury group based in Nashville, Tennessee, with the addition of real estate veteran Grant Hammond, HousingWire reported on Thursday.
Led by Hammond, owner and president of Metropolitan Brokers, along with Tennessee-based Compass agents Brandon Knox and Darin Cunningham, the team has committed to “build, develop and guide” client success and satisfaction.
“As I embark on the next stage of my career, it’s more important than ever to surround myself with people who want to help drive positive change for real estate professionals and consumers,” Hammond said in a statement. “I chose to join Brandon and Darin at Compass because I believe we can be better together and build the most formidable real estate team in the southeastern United States.”
BDG Partners announced on Wednesday that the team collectively closed 6,500 transactions, totaling over $2.85 billion in sales volume.
“All of us have individually been the motivator for our respective teams, driving them forward,” Knox said in a statement.
TAKE THE INMAN INTEL INDEX SURVEY FOR AUGUST
According to HousingWire, Hammond has served on various committees at Greater Nashville, while Knox and Cunningham previously led The Knox Team and The Cunningham Team. The Knox team was ranked as the No.18 small team in Tennessee on the 2024 RealTrends Verified’s City Rankings, with $45.8 million in sales volume in 2023.
“Now we can be motivated by one another and chase a massive goal that is bigger than any of us could accomplish alone while catering to the unique needs of the clients we serve, Knox said.”
BDG Partners will operate out of Compass’ Green Hills and Midtown offices. The team currently has over $350 million in active and pending listings.
“We are honored that Grant, Brandon and Darin have chosen to form and grow their new team at Compass,” Kristy Hairston, the Compass regional vice president overseeing Tennessee, said in a statement. “They embody the spirit of homegrown leadership and community service, and we’re excited to see them grow their business with us.”
Since entering Tennessee in 2018, Compass has made significant moves, including a merger with Parks Real Estate earlier this year, bringing a team of 1,500 agents.
“We are confident that our enhanced presence in the area will continue to benefit all our agents and best serve the community’s real estate ambitions,” Compass Tennessee President Hunter Connelly said in a statement.
Email Richelle Hammiel
by Joseph Santini | Aug 23, 2024 | Industry, News Feed
Zillow is continuing its leadership shuffle, with the Seattle-based residential portal announcing a new senior vice president of agent sales on Friday. Former PayPal executive Soumya Tulloss will lead Zillow’s agent sales, the segment that includes flagship products Zillow Showcase and Zillow Premier Agent.
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
Zillow is continuing its leadership shuffle, with the Seattle-based residential portal announcing a new senior vice president of agent sales on Friday. Former PayPal executive Soumya Tulloss will lead Zillow’s agent sales, the segment that includes flagship products Zillow Showcase and Zillow Premier Agent.

Jun Choo | Credit: LinkedIn
“Zillow is investing in software and digital solutions to power the real estate industry, and that includes a suite of innovative products for agents, who continue to be an integral part of Zillow’s business,” Zillow SVP of Real Estate Software Jun Choo said in a prepared statement. “Organizing our sales teams under Soumya’s leadership allows us to rapidly innovate and strategically invest in our agent community.”
“Soumya’s commitment to exceptional customer experiences, as well as her impressive ability to supercharge sales organizations while driving revenues, make her a valuable addition to the Zillow team,” he added.
Tulloss has 15 years of experience in sales and marketing, starting with an internship with Google where she drove 35 percent of U.S. traffic for the search engine’s Google Maps Favorite Places campaign in 2009. From there, Tulloss went on to work for Deutsche Bank Securities, PayPal, GoodData, Twilio and Deliverr.
At Twilio, she supercharged the company’s revenue growth by more than 3,000 percent, jumping from $89 million in 2014 to $2.8 billion in 2021. She brought that same growth to Deliverr, which reached $2.1 billion in revenue before being acquired by Shopify in 2022.

Soumya Tulloss | Credit: Zillow
In a prepared statement, Tulloss said she’s excited to bring that same growth to Zillow, where she’ll be responsible for driving growth and deeper integration between agent sales solutions and other products within the company.
“I’m excited to support Zillow’s critical mission of getting more and more people home,” she said. “My goal is to make the more than a million agents powering the residential real estate industry wildly successful by offering exceptional services that enable them to serve more customers, more efficiently.”
“As a first-generation American, purchasing and owning a home was a dream for my family,” she added. “The partnership and support we received from our agent helped my family turn that dream into a reality. I’m excited to support our agent customers as we all work together to make this dream a reality for many more people.”
Tulloss’ appointment comes at a critical time for Zillow, as the company aims to stay above the drama of an intensifying portal war and evolve its value proposition to agents as they navigate the dismantling of the National Association of Realtors’ Participation Rule.
During the company’s second-quarter earnings call, Zillow co-founder and co-executive chair Rich Barton and CEO Jeremy Wacksman shared their vision for the portal’s next chapter, which will focus on strengthening the “digital future of real estate” by driving deeper integration between Real-Time Touring, Zillow Showcase and Zillow Premier Agent to create a frictionless transaction experience for agents and consumers.
“We believe we and our partners are the outsized beneficiaries of these changes coming in the industry. We have the most customers. We work with the best partners,” Wacksman said. “We provide the most technology, and we expect our Premier Agents will deliver and get paid because they provide great service.”
In his last Inman Connect Las Vegas keynote as Zillow CEO, Barton said Zillow will continue to accelerate the move toward delivering a platform that will make homebuying and homeselling as easy as buying a latte — an increasingly attractive proposition as agents and consumers wade through a new real estate landscape.
“It’s not unlike Brad Inman’s latte transaction [keynote] from 2013. Who remembers that?” he said. “His vision was organizing this mess and saying moving should be as easy as buying a latte. Well, we’re getting there. We’re getting there. It’s taking a while, but we’re getting there.”
Email Marian McPherson
by Drew Thompson | Aug 23, 2024 | Industry, News Feed
Women’s real estate advocate Bobbie Wasserman shares strategies for overcoming hurdles and obstacles that sometimes block women from optimizing the financial potential of real estate ownership.
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
The real estate commission change is here. As of Aug. 17, 2024, listing agents no longer advertise the commission they are willing to pay — if any — to buyer agents on MLSs. For sellers, the change potentially saves money in the form of less commission paid to their agents. For buyers, it potentially means spending less on home purchases to cover the cost of a real estate agent’s expertise.
For women homebuyers, the new commission landscape might be particularly daunting. According to a Yale School of Management study, single women still lag behind men when it comes to wealth accumulation achieved through home equity.
The study found that women still pay more to buy a home and usually walk away with less profit when they sell.
TAKE THE INMAN INTEL INDEX SURVEY FOR AUGUST
Earlier this year, Zillow teamed up with the National Fair Housing Alliance to survey homebuyers, and the results found that the purchasing process is even more complicated and filled with hurdles for women of color and noted that a racial wealth gap still exists in 2024.
The commission structure change only adds more uncertainty to an already complicated process for some women — particularly regarding the financial implications of the purchase, negotiation dynamics involved in a home purchase and home maintenance.
Financial implications
Women already encounter financial challenges in the homebuying process compared to men — including income disparities, wealth accumulation, financial literacy and confidence, and access to credit. The added burden of formally hiring a buying agent and negotiating a commission could increase the risk of unintentional errors with long-term consequences.
Here are a few tips that can help your female clients better navigate the home purchase process while building trust and credibility in the process.
Understand and acknowledge financial concerns
Take the time to listen to concerns without rushing the conversation. Provide budgeting guides, and offer strategies for leveraging financial assistance programs, grants or lower down payment mortgage options.
The housing affordability crisis has prompted many states to offer special programs. Remember, women can be “first-time” homebuyers at every stage of life — a young professional, a veteran, a seasoned professional, or purchasing a home solo after a divorce or spousal death.
Understand that women process information differently than men and may need more time and information to feel confident in their decisions. You can empower them by giving them all the necessary information and the space to make decisions at their own pace.
Guide your client through the entire home purchase process. If your client encounters obstacles in securing a mortgage, assist them in finding lenders who offer fair terms and explain the importance of comparing loan offers. Demystify the process.
Negotiation dynamics
The vast majority — 89 percent, according to NAR — of homebuyers use real estate agents or brokers to purchase homes, and a major reason for this is the agent’s ability to negotiate effectively.
It is essential to explain your negotiation process and expertise. When working with women homebuyers, providing a more detailed explanation of what to expect can significantly enhance their understanding of the process while demonstrating the value you bring.
Be prepared to discuss the following:
- Negotiation style: Women homebuyers value clarity on how your negotiation approach aligns with their preferences and needs. Share examples of how your negotiation tactics have benefited past clients, and explain what sets your approach apart from other agents.
- Negotiations: Detail how you prepare for successful negotiations and how you plan to involve the buyer in this process. This helps women feel more confident and informed about the steps they will take to secure the best deal.
- Protecting client interests: Clearly outline how you protect your client’s interests during negotiations, especially in situations involving multiple offers or counteroffers. Discuss your strategies for recommending contingencies and ensuring the buyer is well-protected.
- Effective communication: Explain how frequently you provide updates, and involve the buyer in the decision-making process. Effective communication is key to building trust and credibility and ensuring the buyer feels supported throughout the transaction.
- Paying the right price: Describe how you assess the true value of a property before entering negotiations. This can alleviate some financial anxieties and instill more confidence in the process.
Home maintenance planning
The cost of homeownership is a frequent topic of discussion within the Single Lady Estates community. As a buyer agent, you can play a crucial role in setting your clients up for long-term success by emphasizing the importance of maintenance planning right from the start.
By sharing trusted personal contacts — such as dependable contractors and service providers — and recommending popular home maintenance apps, agents can empower new homeowners to take proactive steps in protecting their investments.
Encouraging clients to prioritize these essential aspects early on not only enhances the homeownership experience and safeguards the value of the property but also reinforces an agent’s value.
Remember this
As the real estate commission structure undergoes significant changes, the challenges faced by women homebuyers are more pronounced than ever.
Navigating the financial implications, understanding the nuances of negotiation dynamics and planning for long-term home maintenance are crucial steps that can provide for successful homeownership. Your ability to guide women through these complexities enhances their homeownership experience and solidifies your role as a trusted partner.
Bobbie Wasserman is the founder and CEO of Single Lady Estates, a real estate resources and advocacy company that empowers women through the entire homeownership journey – buying, selling and life in between.
by Rick Guerrero | Aug 23, 2024 | Industry, News Feed
Establishing yourself as a luxury real estate agent doesn’t have to cost more, broker Tara Meier writes. It’s about a simplified aesthetic and a strong sense of your value proposition.
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
Breaking into the luxury real estate market can seem daunting, especially when you are just starting and your bank account isn’t quite where you’d like it to be. However, presenting yourself as a knowledgeable, polished and professional luxury agent does not require a vast budget. It’s about leveraging what you know, how you present yourself and the exceptional service you offer.
TAKE THE INMAN INTEL INDEX SURVEY FOR AUGUST
Here are some essential tips that cost little to nothing but can significantly elevate your positioning against the competition, even if you’re new to the game.
Knowledge and preparation
To exude confidence and competence, become an expert in all things luxury.
- Know the luxury elements: Understand what high-end features go into luxury homes, such as high-end paint brands, premium kitchen appliances, custom furniture and bespoke window coverings.
- Local expertise: Familiarize yourself with local builders, construction companies, architects and ongoing developments. This knowledge will set you apart and position you as an expert in the luxury market.
- Confidence through knowledge: The more you know, the more confident you will be. This confidence will naturally shine through and be recognized by your clients.
Professional appearance
Luxury clients expect professionalism, not necessarily luxury labels.
- Dressed for success: Look put together and professional without trying too hard. Wealthy clients don’t expect you to match their income level but do expect you to present yourself well.
- Smart shopping: Find influencers with styles that resonate with you and look for budget-friendly versions of their looks. Great places to shop include Target, Walmart and Amazon.
- Details matter: Accessories can make a significant difference. A stylish watch, for example, can convey that you value time, a crucial aspect of the luxury world.
Exceptional service
Luxury is not just about products; it’s about the experience.
Anticipate needs: Show clients that you care by anticipating their needs. This demonstrates that exceptional service is a core belief of yours.
- Parking preferences: Before you meet with a client, ask about preferred parking locations to avoid inconveniences.
- Be prepared: Have your presentations downloaded and ready to go, avoiding the need to ask for Wi-Fi passwords. Have a hotspot ready if needed.
Luxury marketing: Have vetted photographers, videographers and other assets ready to showcase your properties.
- Simple and elegant: Luxury marketing should be simple, elevated and elegant.
- Know the competition: Understand what your competitors offer, and be prepared to deliver more or something unique and personalized.
- Value proposition: Know your value, and lean into it confidently.
Authenticity
Faking it till you make it doesn’t work in luxury real estate.
- Honesty: If you don’t know something, don’t make it up. Be honest but not self-critical. Clients will appreciate your authenticity and responsibility.
- Ownership: Own any issues that arise. This will be the expectation, and handling it professionally will reinforce your luxury vibe.
Entering the luxury real estate market doesn’t require a luxury budget, just a strategic approach. By becoming knowledgeable, presenting yourself professionally, offering exceptional service, and being authentic, you can give off that luxe vibe and set yourself apart from the competition.
Remember, luxury is as much about the experience and service you provide as it is about the products themselves.
Jennifer McAlpine is the marketing technology director at MyHome. Connect with her on LinkedIn.



