by Jen Dillard | Jul 29, 2024 | Industry, News Feed
EXp’s Russ Laggan offers tips for identifying your personal and professional style and putting it to work for you as a memorable differentiator with clients and colleagues.
At Inman Connect Las Vegas, July 30-Aug. 1, 2024, the noise and misinformation will be banished, all your big questions will be answered, and new business opportunities will be revealed. Join us.
Do you need to dress to the nines to be taken seriously as a real estate professional? Is professional decorum the same in every market — or even in every brokerage?
As the VP of growth for eXp Realty and a contributor to Inman News, I’ve witnessed firsthand the diverse ways professionalism is perceived in our industry. Unfortunately, real estate agents often grapple with a poor reputation.
According to a recent study by Clever Real Estate:
- 54 percent of recent homebuyers believe their agent cared more about making a deal than their best interests
- 29 percent of buyers went unrepresented, and of those, 32 percent did not hire a real estate agent because they don’t trust them.
This highlights a crucial point: professionalism is not a one-size-fits-all concept. It varies significantly by region and clientele, demanding that we align our image and behavior with the expectations of our market.
To navigate this complexity, consider the following insights:
1. Know that authenticity is crucial
In real estate, authenticity is key. You want to attract clients who resonate with your genuine self, not everyone else. Your presentation should reflect your personality and values. For instance, I often sport a dress shirt, tie, and, if you’ve met me, you know, a vest. I even jokingly wore this attire floating down the lazy river at San Antonio’s JW Marriott. This is my style, and it works for me.
Tony Robbins once emphasized the importance of developing a distinct brand. Embrace what makes you unique — be it a specific style or approach. In a world full of vanilla, be the Rocky Road or Superman ice cream. It’s not about being all things to all people; it’s about being the best version of yourself.
2. Find your tribe
Building successful business relationships is easier when you connect with people who appreciate you for who you are. Pay attention to the unique traits of the people you attract.
Early in my career, many of my clients were fellow mountain bikers. This shared interest fostered trust and solidified our relationships. Consistency — whether in regular meetings or engaging in personal interests — builds reliability and trust. If you aren’t consistent, you’ll struggle to establish yourself as a trustworthy expert.
3. Embrace your uniqueness
Take, for example, tattoos. While my wife might disapprove of tattoos in a professional setting, I proudly display mine — a wedding ring tattoo, a life mantra in my handwriting and my anniversary date.
If a tattoo turns away potential clients, they likely aren’t the right fit for me. I’ve never had issues with clients because of my tattoos, and my style resonates with those who appreciate it.
Jordan Hill, a real estate professional from Oregon, shares similar sentiments. She has visible tattoos and hasn’t faced significant pushback since becoming self-employed. Her experience underscores that tattoos, as long as they aren’t harmful, don’t impede professionalism. The key is to embrace your uniqueness and attract clients who value you for who you are.
Building your brand
Professionalism involves being true to your authentic self. Define your style and align your target market to match. Tailor your messaging to support the client base you are building. By focusing on how you can add value, you’ll attract the right clients and build a supportive community around you.
Embracing authenticity, finding your tribe, and consistently presenting your unique style are guideposts to professional success in real estate. By staying true to who you are and focusing on adding value, you’ll naturally attract the right people and achieve lasting success.
Russ Laggan is a speaker, trainer and eXp’s vice president of growth for the U.S. West. Connect with him on Instagram and LinkedIn.
by Leo Pareja | Jul 29, 2024 | Industry, News Feed
Trust: It’s a leading factor at play when people make important decisions. And in today’s real estate market, where homebuyers and sellers have many options when choosing an agent, they’ll likely go with the one they trust most.
Here are a few ways to ensure your business and marketing practices convey authenticity, confidence and trustworthiness to prospective customers.
Advertise your experience
Many consumers prefer a real estate professional with ample experience through any market conditions. When advertising this experience, it’s important to highlight areas of expertise and real estate specialties, too. This will showcase your breadth of knowledge, increasing the chance of your skills matching their needs.
“People need to experience you before they work with you. One of the most effective ways to build trust in our business is to provide value upfront,” says Todd Stock, Broker/Owner of RE/MAX Results in Fort Wayne, Indiana. “In my brokerage, we provide valuable resources and information to the consumers in our markets – and we let them know what our agents can help with any type of transaction.”
Showcase community involvement
The real estate profession is rooted in community. It makes sense that so many agents get involved in community building – donating their time and resources to improving the lives of others.
This often takes the shape of charitable initiatives. Many members of the RE/MAX network get involved with Children’s Miracle Network (CMN) Hospitals. Since 1992, the RE/MAX network has supported more than 170 affiliate CMN Hospitals across the U.S. and Canada. Earlier this year, it was announced that total RE/MAX donations have surpassed $209 million.
“When people see that we’re committed to giving back and supporting the community – especially CMN Hospitals, which so many people have personal ties to in our area – it shows that we care about more than just business,” Stock says. “Community involvement is crucial because it helps build strong local connections and a positive reputation. Plus, it shows that we’re invested in the well-being of the place where we live.”
Gather reviews from past clients
If your past clients have shared their review of your outstanding service, make sure those remarks are easily accessible by prospective homebuyers and sellers. A great way to instill trust is through word of mouth – whether it comes through conversation, personal recommendations, or online reviews.
“90 percent of my business comes from referrals or past clients, so being able to direct them to my website to check out my reviews helps close the deal for me,” says Angie Lotz, an agent with RE/MAX All Pro in Bloomingdale, Illinois. “Through RE/MAX, agents can customize their websites, which makes each one unique to our businesses. My site allows me to proudly display reviews, which boosts consumer confidence.”
Promote your brand
Brand recognition is an instant way to bolster your credibility. Aligning with a brand that’s a household name to consumers makes for a stronger business foundation — and it’s especially helpful when it’s a brand people trust on local, national and global levels.
Lotz, for example, chooses to align with RE/MAX — a brand with a presence in more than 110 countries and territories – because she finds it garners a high level of respect across consumers and industry professionals alike.
An affiliation like this is also a key way to build trust. Year after year, shoppers have voted RE/MAX as the brand with the #1 Most Trusted Real Estate Agents in the USA* and Canada**.
“Being aligned with RE/MAX definitely helps customers build trust in our business,” says Stock, who has been affiliated with the RE/MAX brand for over 28 years. “People tend to feel more confident working with a company that has a well-known and respected name. It suggests reliability, professionalism, extensive resources and a proven track record, which can make new clients feel more secure in their decision to work with us.”
*Voted most trusted Real Estate Agency brand by American Shoppers based on the BrandSpark® American Trust Study, years 2022-2024 and 2019.
**Voted most trusted Real Estate Agency brand by Canadian shoppers based on the BrandSpark® Canadian Trust Study, years 2021-2024, 2017 and 2019.
by Jeff Tucker | Jul 27, 2024 | Industry, News Feed
At Inman Connect Las Vegas, July 30-Aug. 1, 2024, the noise and misinformation will be banished, all your big questions will be answered, and new business opportunities will be revealed. Join us.
Change is a word that can elicit strong reactions. For some, it brings a sense of excitement and possibility, while for others, it stirs feelings of fear and resistance.
TAKE THE INMAN INTEL INDEX SURVEY FOR JULY
Neuroscience tells us that our brains are wired to seek stability and familiarity, often rewarding us for maintaining the status quo. However, there’s also a growing body of evidence that suggests embracing change can be incredibly rewarding, both psychologically and professionally.
The neuroscience of change
Our brains have evolved to conserve energy, and one way they do this is by encouraging us to stick to routines. Familiar tasks and habits require less cognitive effort and therefore, less energy.
This is why change can sometimes feel uncomfortable — our brains are literally wired to avoid it. But here’s the catch: change can also trigger the release of dopamine, the “feel-good” neurotransmitter, especially when the change is associated with achieving new goals or learning new skills.
For individuals like me, who thrive on new experiences and challenges, this dopamine hit can be incredibly motivating.
René Rodriguez, a dynamic keynote speaker and author of Amplify Your Influence, aptly states, “Our brains are hardwired to avoid change because it requires effort and energy. However, when we embrace change, we activate our brain’s reward system, creating a powerful cycle of growth and improvement.”
Why change is essential
As we move into the second half of 2024, it’s an opportune time to reflect on what changes we need to make to invigorate our real estate careers. Remaining static may feel safe, but it’s not where growth happens.
“At the heart of growth is change. We all strive for innovation, to differentiate and to advance. All of those goals require change. Winning requires change,” Rodriguez writes.
10 things to consider when contemplating a change
In an ever-evolving market, adapting and embracing new strategies sets you apart from the competition. Here’s where to start:
1. Evaluate your goals
Take a moment to reflect on the goals and resolutions you formed at the beginning of this year. Are they still relevant? Do they excite you? Adjust them to align with your current aspirations and market conditions. (Read more about setting and achieving goals.)
2. Adopt new technologies
The real estate industry is rapidly changing with technological advancements. Whether it’s new CRM software, virtual tour platforms, or AI-driven analytics, embracing these tools can streamline your operations and enhance client experiences.
3. Expand your skill set
Invest in professional development. Attend workshops, earn new certifications or explore areas of real estate you haven’t tapped into yet. Broadening your expertise can open new doors and opportunities.
4. Revamp your marketing strategy
If your current marketing efforts are not yielding the desired results, it’s time for a change. Explore new channels like social media advertising, video marketing or content marketing to reach a broader audience.
5. Network and collaborate
Building relationships with other professionals in the industry can provide fresh insights and opportunities. Attend industry events, join professional groups, or collaborate with interior designers and stagers to offer a more comprehensive service to your clients.
6. Reassess your niche
Are you focusing on the right market segment? Sometimes a shift in focus, such as moving from residential to commercial real estate or specializing in luxury properties, can reignite your passion and open up new revenue streams.
7. Improve client communication
Evaluate how you communicate with your clients. Implementing new communication tools, such as automated follow-ups or personalized newsletters, can improve client satisfaction and retention.
8. Optimize your online presence
Your online presence is more important than ever. Update your website, improve your SEO, and increase your activity on social media platforms to attract more leads and establish yourself as an industry expert.
9. Enhance your brand
Your personal brand is your calling card. Consider updating your logo, redesigning your business cards, or creating new marketing materials that reflect your current vision and values.
10. Seek feedback and mentorship
Don’t underestimate the value of external input. Regularly seek feedback from clients and colleagues, and find a mentor who can provide guidance and help you navigate challenges.
Bonus tip: Pick up the phone
Have you ever heard of phone anxiety or telephonophobia? It’s a surprisingly common phenomenon for a population that relies primarily on emails and texts for communication, but nothing beats the personal touch of a phone call.
Picking up the phone to connect with clients, potential leads, or colleagues can foster stronger relationships and clear up misunderstandings quickly. A simple phone call can demonstrate your commitment and attentiveness, leaving a lasting positive impression.
When you’re in a time of change, don’t underestimate the power of a phone conversation to help you gain clarity, make plans and seek out solid advice from mentors.
Embrace the excitement of change
Change doesn’t have to be daunting. It can be exhilarating and full of potential. As we dive into the latter half of 2024, ask yourself: What changes do I need to make to feel excited about my career? What activities should I pivot to drive the results I want?
For those who resist change, remember that it can be a catalyst for growth and innovation. It’s time to step out of your comfort zone and embrace the endless possibilities that change brings.
Change fires me up. It pushes me to improve and grow continuously. As you consider your own journey, remember that change is not just good; it’s essential for success in the real estate world. Let’s make the second half of 2024 not just different but better than what came before.
Troy Palmquist is the vice president of growth and product marketing for eXp California. Follow him on Instagram or connect with him on LinkedIn.
by Brian Donnellan | Jul 27, 2024 | Industry, News Feed
Industry analyst Ryan Tomasello, who predicted a 30 percent fall in commissions due to legal, economic and governmental challenges, prepares to take the stage at Inman Connect Las Vegas to discuss consolidation, disruption and innovation.
At Inman Connect Las Vegas, July 30-Aug. 1, 2024, the noise and misinformation will be banished, all your big questions will be answered, and new business opportunities will be revealed. Join us.
Each week on The Download, Inman’s Christy Murdock takes a deeper look at the top-read stories of the week to give you what you’ll need to meet Monday head-on. This week: Industry analyst Ryan Tomasello, who predicted a 30 percent fall in commissions due to legal, economic and governmental challenges, prepares to take the stage at Inman Connect Las Vegas to discuss consolidation, disruption and innovation.
As a managing director at global wealth management and investment banking company Keefe, Bruyette & Woods, Ryan Tomasello leads the firm’s research coverage of fintech and real estate technology.
Tomasello and his firm first made waves back in October, releasing a report predicting the loss of a million Realtors and a 30 percent dip in commissions if the Department of Justice and buyer- and seller-initiated legal maneuvers resulted in a ban on cooperative compensation. That was before the Halloween verdict in the Sitzer | Burnett trial and the subsequent March settlement from the National Association of Realtors.
EXTRA: NAR to shed 1M members if shared commission banned, analysts say
This week, Tomasello will take the stage at Inman Connect Las Vegas to talk about industry consolidation, disruption and potential innovation. Matt Carter sat down with Tomasello for a pre-ICLV Q&A to learn more about what he calls a “watershed moment” for the real estate industry.
While Tomasello and his firm throw around some big numbers when predicting changes in the industry, he took pains to explain that those changes won’t be immediate.
“I think the key caveat there is that it’s likely to take time,” Tomasello said. “It’s not something that will happen overnight. As much debate as there’s been around how much commissions will decline, there’s an equal amount of debate around how long this impact will take to play out.”
Check out Carter’s interview with Tomasello and, if you’re in Vegas this week, don’t miss his Wednesday morning main stage appearance. Can’t make it in person? Grab your virtual ticket here for the livestream.
As always, we’re laser-focused on bringing you all of the information you need to navigate the new normal — without letting your business fall victim to any potential negative effects. This week, we’re sharing ideas to help you build and scale, embrace the potential of M&A, fine-tune your marketing and pivot to a seller focus.
In addition, in this week’s Pulse survey, we want to find out what questions still haven’t been answered adequately from your perspective. Your answers will help drive the content we provide in the weeks ahead.
Entrepreneurship isn’t just good for individual real estate pros, PR and marketing expert Molly McKinley writes. It’s good for organizations and for the industry as a whole.
EXTRA: Forget mega-agent recruiting. Recruit brokerages instead
Consumers expect specialization in every area of life, from doctors to hairdressers, coach Verl Workman writes. They should expect no less from their real estate expert when it’s time to sell.
EXTRA: Demystifying KPIs and essential marketing metrics
Buyer agreements for open houses? Workarounds? Concessions? As agents race to comply with terms of the NAR settlement on Aug. 17, Inman wants to help answer your toughest questions.
by Ken Baris | Jul 26, 2024 | Industry, News Feed
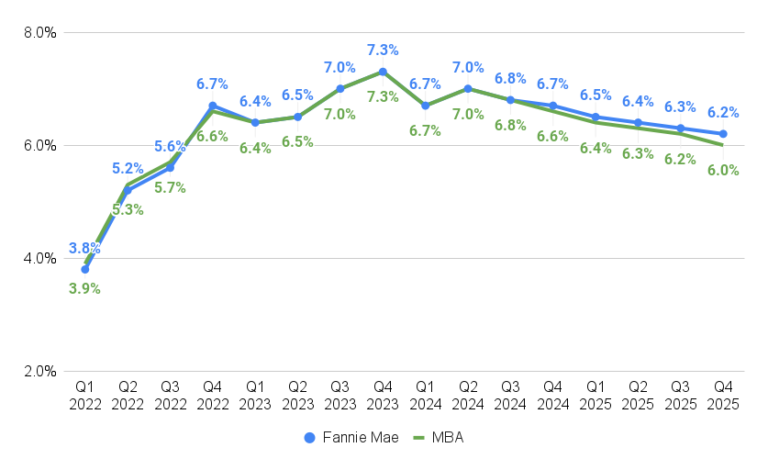
As inflation gets closer to Fed’s 2 percent target, economists at Fannie Mae and the Mortgage Bankers Association predict mortgage rates will continue to drop into the low sixes by the end of next year.
At Inman Connect Las Vegas, July 30-Aug. 1 2024, the noise and misinformation will be banished, all your big questions will be answered, and new business opportunities will be revealed. Join us.
After holding steady for two weeks, mortgage rates look poised to resume a pullback from 2024 highs, after the Federal Reserve’s preferred measure of inflation fell for the third month in a row.
TAKE THE INMAN INTEL INDEX SURVEY FOR JULY
The personal consumption expenditures (PCE) price index fell to 2.51 percent in June from a year ago, just half a percentage above the Fed’s 2 percent target, the Commerce Department’s Bureau of Economic Analysis reported Friday.
Core PCE, which excludes the cost of food and energy and can be a more reliable indicator of underlying inflation trends, was up 2.63 percent from a year ago, essentially flat from May.
PCE and Core PCE trending down
“We see a decent chance that core PCE hits 2 percent in the middle of next year, much sooner than the Fed’s forecast,” Pantheon Macroeconomics Chief Economist Ian Shepherdson said in a note to clients. Projections issued by Fed policymakers in June showed they didn’t expect inflation to hit 2 percent until 2026.

Ian Shepherdson
“If we’re right, the clear and obvious progress towards the target across [the second half of 2024], coupled with a loosening of the labor market, will push the Fed into easing much more quickly than their current forecasts,” Shepherdson predicted.
Pantheon Macroeconomics is predicting the Fed will cut short-term interest rates by 1.25 percentage points this year, starting with a 25 basis-point cut in September, followed by 50 basis-point reductions in November and December. A basis point is one-hundredth of a percentage point.
That would bring the federal funds rate to between 4 percent and 4.25 percent, down from the current target of 5.25 percent to 5.50 percent.
Futures markets tracked by the CME FedWatch Tool show investors aren’t anticipating the Fed will cut that drastically. As of Friday, futures markets investors put the odds that the Fed will cut rates by at least 75 basis points this year at 65 percent, and only about a 7 percent chance for deeper cuts.
The latest PCE data came on the heels of a surprisingly strong gross domestic product (GDP) report released Thursday. The advance estimate from the Bureau of Economic Analysis put second-quarter GDP growth at 2.8 percent, up from 1.4 percent in Q1.
That rate of growth “was undeniably robust, easily beating both our own and the consensus forecasts,” economists at Pantheon said in their July 26 U.S. Economic Monitor. “Looking under the hood, however, we see good reasons to think this strength will be short-lived.”
The biggest driver of Q2 GDP was stronger than expected government spending, Pantheon economists said, which “looks unlikely to be repeated, given the pressure that much weaker revenue growth is putting on state and local government finances.”
Yields on 10-year Treasury notes, a barometer for mortgage rates, dropped 6 basis points Friday after the release of the June PCE price index. Treasury yields had climbed by about the same amount Thursday on the strong GDP report.
Rates for 30-year fixed-rate conforming mortgages averaged 6.77 percent Thursday, down half a percentage point from a 2024 high of 7.27 percent registered on April 25, according to rate lock data tracked by Optimal Blue.
A survey by Mortgage News Daily showed rates on 30-year fixed-rate mortgages were down 5 basis points Friday, back to about where they were a week ago.
Economists at Fannie Mae and the Mortgage Bankers Association (MBA) predict mortgage rates will continue to drop into the low sixes by the end of next year.
Mortgage rates projected to ease
The recent decline in mortgage rates hasn’t sparked a rush to buy homes, with a weekly MBA survey of lenders showing requests for purchase loans fell by a seasonally adjusted 4 percent during the week ending July 19 when compared to the week before, and was off 15 percent from a year ago.
A series of encouraging consumer price index (CPI) reports have also raised expectations that the Fed will ease, although Federal Reserve Chair Jerome Powell and other policymakers at the central bank have consistently warned that they won’t cut rates until they’re convinced inflation has truly been tamed.
That was the gist of remarks Fed Governor Christopher Waller made on July 17, following the release of a CPI report showing price appreciation cooled to 3 percent annually in June.

Christopher Waller
“On the one hand, it is essential that monetary policy get inflation down to a sustained level of 2 percent,” Waller said. “If we start to loosen policy too soon, and allow inflation to flare up again, we risk losing credibility with the public and allowing expectations of future inflation to become unanchored.”
The credibility the Fed has gained by keeping rates elevated “has helped inflation fall as quickly as it has in the past 18 months and squandering it would be a grave mistake,” Waller said. “Monthly PCE inflation has very recently been running near 2 percent at an annual rate, but I need to see a bit more evidence that this will be sustained.”
Waller also acknowledged that there’s also a risk that if the Fed waits too long to cut rates, that could contribute to “a significant economic slowdown or a recession, with unemployment rising notably.”
Get Inman’s Mortgage Brief Newsletter delivered right to your inbox. A weekly roundup of all the biggest news in the world of mortgages and closings delivered every Wednesday. Click here to subscribe.
Email Matt Carter
by Drew Thompson | Jul 26, 2024 | Industry, News Feed
JND Legal Administration, the company tapped by lawyers to oversee administrative tasks around the Gibson settlement, sent mail out to millions of potential class members earlier this year.
At Inman Connect Las Vegas, July 30-Aug. 1, 2024, the noise and misinformation will be banished, all your big questions will be answered, and new business opportunities will be revealed. Join us.
More than 10 million homesellers have been — or will be — inundated with notices that they might be entitled to receive payment from the proposed commission settlements by a handful of real estate brokerages.
JND Legal Administration, the company tapped by lawyers to oversee administrative tasks around the commission lawsuit known as Gibson, has sent more than 10 million postcard notices to potential class members, as well as more than 27 million email notifications, since March, according to additional legal documents JND provided to Inman.
JND is also running ad campaigns across print, TV and digital media to further reach consumers who might be able to file claims, according to the documents. The efforts highlight both the massive scope of the settlements, as well as highlight the fact that they are moving forward outside the courtroom.
TAKE THE INMAN INTEL INDEX SURVEY FOR JULY
“If you sold a home and paid a commission to a real estate agent, then you may be part of class action settlements,” the notice states. Already, more than 700,000 of the postcards have been returned as undeliverable.
Homesellers have until May 9, 2025, to submit a claim form by mail or on the website www.RealEstateCommissionLitigation.com.
Alternatively, they have until Oct. 3 to ask not to be included in the settlements, or to object to them.
A final public hearing regarding the settlements by Compass, Real, Redfin, Realty One, @properties, Douglas Elliman, Engel & Volkers, HomeSmart and United Real Estate is scheduled for Oct. 31.
Not every brokerage listed in the Gibson suit has reached a settlement agreement, and the total settlement pool could grow in the weeks ahead. EXp Realty is the largest firm to not yet reach a settlement agreement.
Homesellers might be eligible if they listed their homes in the following areas and timeframes:
- On an MLS in Alabama, Georgia, Indiana, Maine, Michigan, Minnesota, New Jersey, Pennsylvania, Tennessee, Vermont, Wisconsin, or Wyoming between Oct. 31, 2017 and July 23, 2024
- On an MLS in Nevada between Jan. 15, 2018 and July 23, 2024
- On an MLS in Arkansas, Kentucky, or Missouri between Oct. 31, 2018 and July 23, 2024
- On an MLS in California between Oct. 2, 2019 and Jul 23, 2024
- On an MLS anywhere in the United States, other than in the states listed above between Oct. 31, 2019 and July 23, 2024.
In total, the brokerages listed above have agreed to pay over $110 million, collectively. The total is over $730 million when including settlements from the National Association of Realtors, HomeServices of America, Keller Williams and others.
Plaintiffs’ attorneys are entitled to receive up to 33.3 percent of the total, plus out of pocket expenses incurred during the case.
Email Taylor Anderson