Dip in mortgage rates doesn’t do much to excite homebuyers

Dip in mortgage rates doesn’t do much to excite homebuyers

While purchase loan demand was still up 18 percent last week from a year ago, some of that demand may not translate into sales, with Redfin reporting an unusual bump in cancelled purchase contracts.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

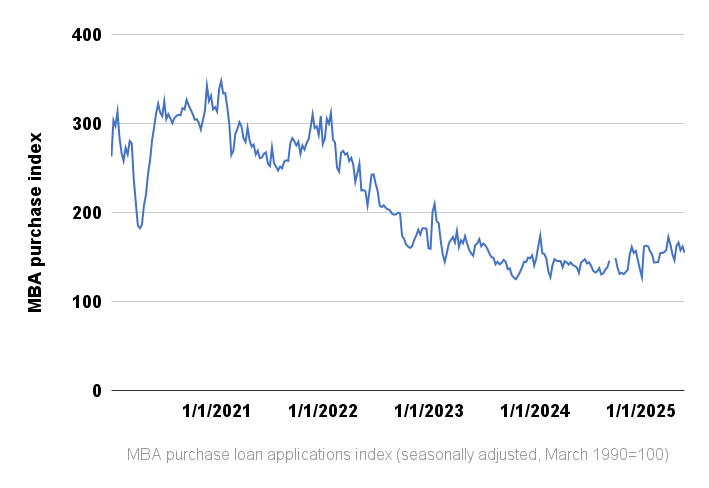
Last week’s dip in mortgage rates didn’t send homebuyers rushing to their lender, with purchase loan applications contracting by a seasonally adjusted 4 percent compared to the week before, according to a weekly survey of lenders by the Mortgage Bankers Association (MBA).

The latest MBA Weekly Mortgage Applications Survey, released Wednesday, found purchase loan demand was still up 18 percent from a year ago. However, some of that demand may not translate into sales, with Redfin reporting an unusual bump in cancelled purchase contracts in April.

The MBA survey showed requests to refinance were down 4 percent during the week ending May 30 when compared to the week before, but up 42 percent from a year ago.

Joel Kan

“Most mortgage rates moved lower last week, with the 30-year fixed rate declining to 6.92 percent and staying in the 6.8 percent to 7 percent range since April,” MBA Deputy Chief Economist Joel Kan said in a statement.

“Refinance activity fell across both conventional and government segments, and the overall average refinance loan size was the smallest since July 2024, as potential borrowers hold out for larger rate drops,” Kan said.

Redfin’s analysis of MLS pending-sales data showed 14 percent of homes that went under contract in April — about 56,000 properties — ended up not selling because their purchase agreements were cancelled.

That’s the second highest share of April cancellations in records dating back to 2017, Redfin said, after April 2020, when the pandemic put the brakes on many closings.

Redfin said purchase agreements are being cancelled at a higher rate than usual during the spring homebuying season due to economic and political uncertainty, a surge of inventory in many markets, and elevated home prices and mortgage rates.

Mortgage rates on the rebound

Since hitting a 2025 low of 6.48 percent on April 4, rates on 30-year fixed-rate conforming mortgages have rebounded above 6.8 percent for most of May, according to lender data tracked by Optimal Blue.

Inflation continued to move closer to the Federal Reserve’s 2 percent target in April, but central bank policymakers have been reluctant to cut short-term interest rates as they continue to assess the impacts of the Trump administration’s policies in areas including tariffs, immigration, taxes and regulation.

Purchase loan demand peaked in April

Even after adjusting for heightened demand during the spring homebuying season, purchase loan requests peaked in April, MBA data shows.

At 155 for the week ending May 30, the MBA’s seasonally adjusted purchase index was at its lowest reading since the week ending April 25. The index is now down 18 points from its 2025 high of 172.7 registered during the week ending April 4, but 27 points higher than a low for the year registered in January.

Get Inman’s Mortgage Brief Newsletter delivered right to your inbox. A weekly roundup of all the biggest news in the world of mortgages and closings delivered every Wednesday. Click here to subscribe.
Email Matt Carter

Wells Fargo free to grow again after Fed lifts $1.95T asset cap

Wells Fargo free to grow again after Fed lifts $1.95T asset cap

Lifting of the asset cap could give the bank greater leeway to originate jumbo mortgages that exceed Fannie Mae and Freddie Mac’s $806,500 conforming loan limit in most markets.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

Wells Fargo has freed itself from a $1.95 trillion asset cap that limited its growth for nearly a decade, with the Federal Reserve Board certifying Tuesday that the bank has put “widespread consumer abuses and other compliance breakdowns” behind it and improved its governance and risk management program.

The Fed imposed the asset cap in 2018, in the wake of a series of scandals, including “cross-selling” practices in which bank customers were enrolled in new deposit and credit card accounts without their knowledge.

“Wells Fargo pursued a business strategy that prioritized its overall growth without ensuring appropriate management of all key risks,” federal regulators said in imposing the asset cap. “The firm did not have an effective firm-wide risk management framework in place that covered all key risks. This prevented the proper escalation of serious compliance breakdowns to the board of directors.”

Tuesday’s lifting of the asset cap “represents successful remediation to the required standard based on focused management leadership, strong board oversight, and strict supervision holding the firm accountable,” Federal Reserve Governor Michael Barr said in a statement. “All three will need to continue for the firm to have a sustainable approach.”

Wells Fargo CEO Charlie Scharf said Wells Fargo is “a different and far stronger company today because of the work we’ve done” to address past problems.

Since 2019, the bank has closed 14 consent orders imposed by regulators over its business practices.

Wells Fargo announced in January that the Consumer Financial Protection Bureau had lifted a 2022 consent order related to a $3.7 billion settlement over the bank’s alleged mismanagement of mortgages, auto loans and deposit accounts.

On May 29, Wells Fargo said it had closed a 2015 consent order with the Office of the Comptroller of the Currency, leaving only the 2018 consent order with the Federal Reserve Board in place.

Wells Fargo has “changed and simplified our business mix, and we have transformed the management team and how we run the company,” Scharf said in a statement Tuesday.

“We have been methodically investing in the company’s future while improving our financial results and profile. We are excited to continue to move forward with plans to further increase returns and growth in a deliberate manner supported by the processes and cultural changes we have made.”

Lifting of the asset cap could give the bank greater leeway to originate jumbo mortgages that exceed Fannie Mae and Freddie Mac’s $806,500 conforming loan limit in most markets. Lenders who make such loans often hold them on their balance sheet, since they’re more difficult to bundle up and sell to investors.

Once the nation’s largest mortgage lender, Wells Fargo was overtaken by direct lender Quicken Loans (now Rocket Mortgage) in 2017 and fell out of the top 10 in the face of regulatory issues, a shrinking branch footprint and rising interest rates.

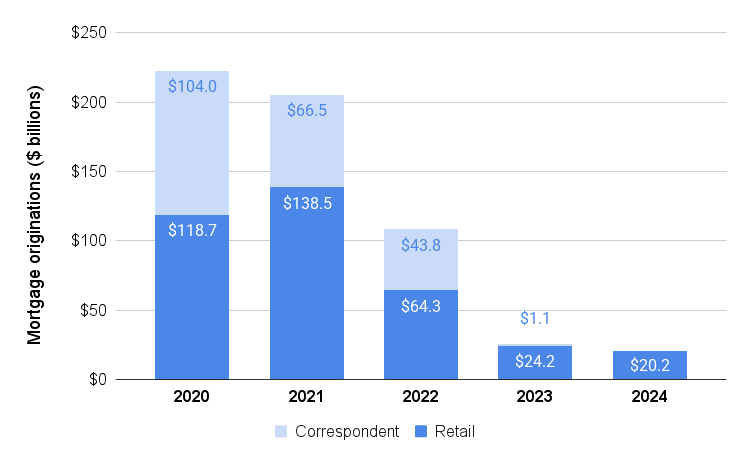
Wells Fargo mortgage originations, 2020-24

Source: Wells Fargo earnings reports.

When borrowers rushed to refinance during the pandemic, Wells Fargo originated $223 billion in mortgages in 2020 — more than 10 times as much business as it did last year ($20.2 billion).

Scharf has said Wells Fargo is “not interested in being extraordinarily large in the mortgage business, just for the sake of being in the mortgage business.”

But theoretically, technology like artificial intelligence employed by the nation’s biggest mortgage lenders — UWM and Rocket — could allow Wells Fargo to rapidly scale its mortgage business despite its reduced branch office footprint and staffing levels.

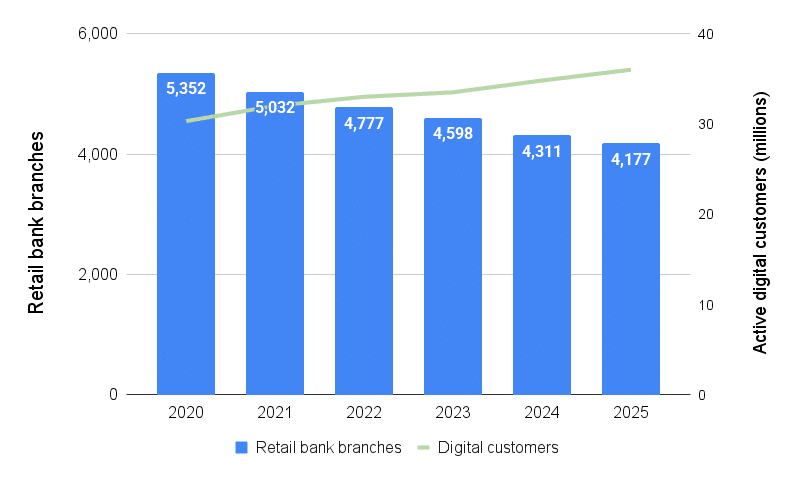
Wells Fargo closing branches, growing digital customer base

Retail bank branch and digital customer count at the beginning of the year. Source: Wells Fargo earnings reports.

Wells Fargo ended 2024 with 4,177 retail bank branches, down 22 percent from 5,352 at the beginning of 2020.

But a growing number of customers — 36 million at the beginning of the year — access the bank online or through mobile devices, up 19 percent since the beginning of 2020.

Get Inman’s Mortgage Brief Newsletter delivered right to your inbox. A weekly roundup of all the biggest news in the world of mortgages and closings delivered every Wednesday. Click here to subscribe.
Email Matt Carter

Redfin shareholders approve Rocket merger at special meeting

Redfin shareholders approve Rocket merger at special meeting

With antitrust regulators declining to weigh in, $1.75 billion deal to marry a tech-focused mortgage lender to real estate brokerage could close by the end of the month.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

Redfin shareholders on Wednesday signed off on the company’s agreement to be acquired by mortgage lending giant Rocket Companies, clearing the way for the deal to close this month.

The $1.75 billion merger agreement was approved by Redfin shareholders at a special meeting Wednesday, according to preliminary voting results.

The window for antitrust regulators to weigh in with questions or objections to the deal closed on May 8. In reporting first quarter earnings, Rocket executives said they expected to close the deal as soon as this quarter, which ends June 30.

Five Senate Democrats on Wednesday condemned Rocket’s plans to acquire Redfin and Mr. Cooper, and asked why antitrust regulators at the Department of Justice and Federal Trade Commission declined to challenge the Redfin merger.

“At a time when families already face a housing affordability crisis, these deals would combine the second-largest mortgage originator, the largest mortgage servicer, and the third-most-visited real estate brokerage website in the United States, into a massive, vertically integrated conglomerate that may reduce choice and raise prices for American families in the housing market,” Senate Democrats including Elizabeth Warren, Bernie Sanders and Cory Booker wrote regulators.

“Instead of competing for new customers by offering better products and services, Rocket is attempting to acquire two already massive companies to create a single, vertically integrated conglomerate,” the lawmakers claimed. “Rocket’s proposed acquisitions of Redfin and Mr. Cooper create the potential for Rocket to steer homebuyers to its own products, hike prices based on private data, and block competition.”

In a pitch to investors in March, Rocket executives said that by handling every aspect of homebuying and selling — from home search to mortgage financing and title and closing — transaction costs on the median priced home will drop from $40,000 to $20,000.

Redfin shareholders had filed four lawsuits complaining that shareholders were entitled to more information about the deal. Attorneys for Redfin shareholder Jason Morano, for example, sought class action certification to represent shareholders they claimed were left in the dark by a “materially incomplete and misleading” deal proxy statement.

Morano’s May 9 complaint sought a court order preventing Redfin shareholders from voting on the merger until they’ve received more details on Redfin deal advisor Goldman Sachs’ dual role as a lender to Rocket.

In a May 29 proxy statement, Redfin executives said all four lawsuits “are without merit, that no supplemental disclosures are required under applicable law, and that the requested additional disclosures are immaterial.”

Rocket, which also has its sights set on acquiring the nation’s biggest loan servicer, Mr. Cooper, says acquiring Redfin will help it achieve its goal of capturing 8 percent of the purchase loan market, and the $9.4 billion Mr. Cooper deal will put Rocket in touch with more homeowners who might be ready to refinance.

Rocket wants to handle 20 percent of U.S. mortgage refinancings, and Rocket CEO Varun Krishna said last month that the company has invested about $500 million in AI and other technology that will help the company scale its business without a proportionate increase in expenses after the mergers.

Rocket announced this week that it plans to issue $4 billion in debt and use the proceeds to retire notes held by Mr. Cooper subsidiary Nationstar Mortgage Holdings Inc.

Editor’s note: This story has been updated to include criticism of Rocket’s plans to acquire Redfin and Mr. Cooper by Senate Democrats. 

Get Inman’s Mortgage Brief Newsletter delivered right to your inbox. A weekly roundup of all the biggest news in the world of mortgages and closings delivered every Wednesday. Click here to subscribe.
Email Matt Carter

DOJ removes Nosalek settlement objection — with a strong warning

DOJ removes Nosalek settlement objection — with a strong warning

The federal law enforcement agency withdrew objections to a fourth proposed settlement between plaintiffs and MLS PIN Tuesday, but cautioned that the MLS was not immune to future legal action.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

The U.S. Department of Justice (DOJ) has withdrawn its objection to the settlement between plaintiffs and MLS Property Information Network (PIN) in the homeseller commission lawsuit known as Nosalek, according to a response the DOJ filed in the case on Tuesday.

The move by the government agency follows homeseller plaintiffs and defendant MLS PIN submitting a fourth amended settlement agreement last week, which stipulates that offers of cooperative compensation will be prohibited on MLS PIN’s platform (something other MLSs did in the settlement of commission lawsuit case Sitzer | Burnett) and raises the proposed settlement fund from $3 million to $3.95 million, the same amount it would have cost MLS PIN to join NAR’s settlement in Sitzer | Burnett.

The DOJ’s response specified that it was not taking any position on whether or not the proposed settlement was “fair, reasonable, and adequate” so that the court could approve it without influence from the agency. The DOJ also reiterated that it believes “blanket, upfront offers” of buyer broker compensation from homesellers or their agents are anticompetitive in practice and lead to inflated home prices.

Furthermore, even though the parties reached a proposed settlement, it does not mean that they are shielded from “future enforcement actions” by the government, the filing stated. And, if MLS PIN indeed follows the terms of the settlement, that action in itself would not be a defense, should the government decide to take legal action against the MLS in the future.

“Because the proposed settlement was reached between private litigants in a private class action suit, such settlement does not preclude any future enforcement actions by the United States,” the DOJ’s response said. “Nor would compliance with the proposed settlement or new MLS PIN rules implementing that settlement afford a defense to any such enforcement actions.”

If such a warning by the DOJ is true in the Nosalek case, it may also apply to settlements arranged with parties involved in other commission lawsuit cases with approved settlements — which should keep major industry players on their toes.

A preliminary settlement approval hearing is scheduled for June 10 in Massachusetts federal court.

Other defendants in the Nosalek case, including HomeServices of America, Keller Williams, Anywhere and RE/MAX, have all now been granted final approval of their settlements.

Email Lillian Dickerson

What’s your elevator pitch to ‘I found it on Zillow’ buyers? Pulse

Since the NAR commission suit settlement, buyer agents have faced new rules, new documents and a new normal. This month, Inman drills down on Today’s Buyers Agent with the fresh marketing strategies, skills and tools buyer agents are using to prosper in changing times.

Pulse is a recurring column where we ask for readers’ takes on varying topics in a weekly survey and report back with our findings.

“But the Zestimate said…”

Those words are sure to send chills down the spines of buyer and seller agents alike. Many potential clients show up to their first conversation with you armed with the online research they’ve done that convinces them they’re a real estate expert. While they may know a lot, you know more. But how do you convince them of that?

When someone says they’ve already figured it all out, what do you say? How do you differentiate your service from anonymous online advice? How do you talk about home values with someone who’s a Zillow-based expert? How do you redirect a client who’s going down the wrong path based on their web-based research? Let us know below:

We’ll compile a list of the top responses and post them on Inman next Tuesday.

Why your brokerage needs a service, not just sales, funnel

Why your brokerage needs a service, not just sales, funnel

Focus on the client lifecycle to build loyalty and enhance brand reputation, ultimately driving retention, The Agency’s Rainy Hake Austin writes.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

An effective sales funnel converts leads into closed deals — spanning the client journey from brand awareness through conversion into a purchase or sale. It’s important to remember that the client lifecycle and the transaction lifestyle are not one and the same — and your transaction expertise, on its own, isn’t enough to build a sustainable real estate business.

While creating a robust, functional sales funnel is a key part of real estate marketing, it’s only part of the equation. An effective client service funnel exceeds expectations, making each person feel seen, heard, valued, and supported, and turns clients into super-fans and super-fans into advocates for you and your brokerage. A client service funnel takes things further — to client retention, loyalty and even advocacy.

Fundamentally, we’re in a client service business where every touchpoint counts. You know you’ve done your job well when your clients become your biggest cheerleaders. I contend that a successful client journey isn’t possible without a top-notch client service funnel. In this article. I’ll share why you need one and how to build one to drive brand loyalty, reputation — and ultimately, repeat business and referrals

Sales funnel vs. client service funnel

A sales funnel assumes that every person in your network and each new contact you make is planning to buy or sell this summer — or this year. And they’re not. Real estate is a long game that requires that you nurture every contact, lead, prospect and client relationship — for years and even decades.

The goal is to stay top-of-mind so that when they’re ready to buy or sell, they’ll think of you first. How to make that happen? By surprising and delighting every client through the lifecycle of their transaction, and at every touchpoint thereafter, nurturing your relationship for years. 

Key benefits of a client service funnel

At a recent company-wide meeting, we talked about providing unreasonable hospitality — a concept popularized by author and world-class restaurateur Will Guidara. As an example, The Agency’s CEO and founder, Mauricio Umansky, shared how he likes to chauffeur his clients to showing appointments whenever possible. It’s kind of his thing, and it’s this type of attention to detail that has made Mauricio and The Agency so successful.

The tangible benefits of a well-honed client service funnel include stronger client relationships, higher client retention rates, a deeper client connection with your brand and, ultimately, more repeat and referral business. Collectively, these build a strong foundation for a sustainable, enduring and thriving real estate career.

How to create an exceptional client service funnel

So how do you establish a client service funnel that surprises, delights and crafts exceptional client experiences at every stage of the transaction — and indeed, at every touchpoint in your client relationships? Here are just a few ways to make lasting impressions that your clients will talk about to friends and colleagues for years to come. 

  1. Actively listen and connect: Make active listening your superpower because a truly intuitive understanding of your client’s needs, desires, concerns and lifestyle will help you make curated property recommendations and give advice that truly aligns with their preferences and goals. Connect on their preferred platforms (such as text, phone, email or social media); even if you prefer text messaging, pick up the phone if that’s how your client prefers to connect. 
  2. Personalize your communication: Tailor your messaging according to each client. Use your CRM systems to track each touchpoint, important dates and their personal details to make each client interaction feel authentic, relevant and timely. Maintain open lines of communication and respond promptly to show your clients that their needs, questions and concerns are your top priority.
  3. Proactively problem-solve: Anticipate and solve problems before they escalate to show your commitment to your client’s comfort and well-being. Demystify complex terminology and processes, share valuable info about desired neighborhoods or market trends, and recommend service providers, local contractors or vendors. Stay one step ahead by identifying potential roadblocks in the transaction process and present solutions before your client even realizes there might be an issue. 
  4. Be a trusted advisor: A consistent track record of successful closings helps build client confidence, but nothing works as well as demonstrating your genuine desire to support your client’s best interests and goals beyond the fundamentals of their transaction. Consistently deliver on your promises and provide honest guidance, even and especially when you have to say the hard things.
  5. Create memorable client experiences: Design unforgettable moments throughout the client journey — whether through creative marketing strategies for their listing, thoughtfully selected closing gifts or exclusive client appreciation events. A thoughtful check-in after their purchase or sale to address concerns and offer ongoing support reinforces your commitment to them, beyond the scope of the transaction. 

Embracing a client service mindset

Agents who embrace a client service mindset in everything they do — turning ordinary interactions into extraordinary experiences — are the ones who truly excel. Once the signatures are dry, client retention requires ongoing support, knowledge sharing, consistent communication and relationship building — all working together to earn loyalty that can transform your clients into advocates who’ll sing your praises. 

When you consistently deliver unreasonable hospitality and exceptional service, you build a legacy of trust that becomes the cornerstone of your long-term real estate success, generating repeat and referral clients that will be the mainstay of your business for decades to come.