Naples estate shatters Florida home sale record with $225M sale
A sprawling waterfront estate in Naples, Florida, has shattered records with its $225 million sale, making it the most expensive residential transaction in state history and the second-priciest in the country, the Wall Street Journal reported Friday.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the Inman Community and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

A sprawling waterfront estate in Naples, Florida, has shattered records with its $225 million sale, making it the most expensive residential transaction in state history and the second-priciest in the country, the Wall Street Journal reported Friday.

The current national record remains with Citadel CEO Ken Griffin, who paid $238 million for a New York City penthouse at 220 Central Park South in 2019. In Florida, the previous high was set by Oracle founder Larry Ellison’s $173 million purchase of a Manalapan estate in 2022.

TAKE THE INMAN INTEL SURVEY FOR APRIL

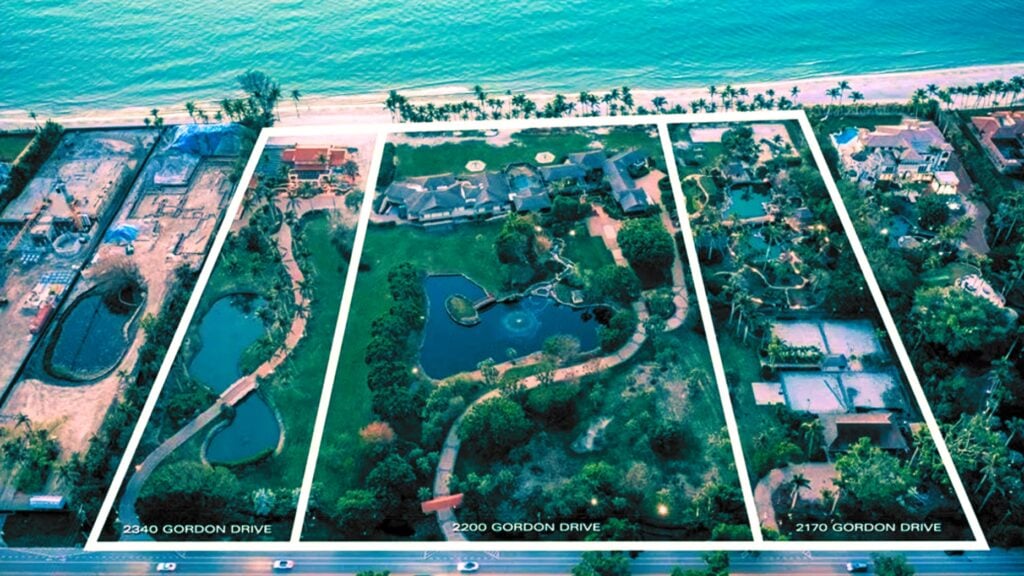
The newly sold Naples estate sits on Gordon Drive in the exclusive Port Royal community, prized for its exclusivity and access to the private Port Royal Club. Spanning about 15 acres with 800 feet of direct Gulf frontage, the Naples estate represents one of the largest waterfront properties in the country.

Michael McCumber of Gulf Coast International Properties represented the seller — a party tied to the Canadian DeGroote family. The buyer’s identity has not been disclosed.

Originally listed for $295 million in early 2024, the estate ultimately sold for a significant price reduction. Still, McCumber emphasized that the property offers a “once in a lifetime, singular opportunity to build a true legacy,” per the property’s listing description.

The estate is made up of three contiguous parcels: a southernmost property with a 6,000-square-foot home built in 1938 (which survived Hurricane Ian without water damage), an undeveloped three-acre lot and another parcel boasting waterfront access. Together, the properties could be reimagined into up to five oceanfront estates.

Beyond the sheer size and waterfront appeal, the new owner will also be part of Port Royal’s next chapter.

“Port Royal is undergoing a remarkable transformation, with the $100 million reconstruction of its private beach club driving a new era of luxury living,” McCumber said in a statement. “By closing this record-breaking deal, we’ve once again raised the bar.”

Across the national luxury market, other massive deals include Oakley founder James Jannard’s record-setting $210 million sale of his Malibu compound in 2024. Meanwhile, Jeff Bezos has continued to expand his portfolio, snapping up three properties worth a combined $237 million in Miami’s “Billionaire Bunker” enclave of Indian Creek Village. Bezos also broke Washington’s most expensive sale record for his Hunts Point, Washington, estate, sold for $63 million earlier this month.

Back in Naples, another major transaction is in the works. Activist investor David Hoffman is reportedly closing on a deal for a waterfront estate priced north of $100 million, as reported by Naples Daily News.
Email Richelle Hammiel

This post was originally published on this site

Patrick Carroll evades prosecution with mental health counseling

The multifamily investor has agreed to undergo mental health counseling and, in doing so, will not be prosecuted on felony charges by the LA County District Attorney’s Office, according to a pretrial hearing last week.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the power of the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

Multifamily investor Patrick Carroll will avoid criminal charges against him after consenting to counseling in a pretrial hearing that occurred last Thursday.

Carroll was facing felony charges for displaying a loaded firearm in public last summer and evading arrest by law enforcement, which was captured in news footage. Carroll pleaded not guilty and said in November that he has bipolar disorder.

Carroll said during the pretrial hearing last week that he would enter a mental health diversion program in exchange for the LA County District Attorney’s Office dropping his case, according to court records, The Real Deal reported.

Over the past couple of years, Carroll has had a number of encounters with law enforcement and has been the subject of multiple civil lawsuits from his former employees. In 2023, he sold his multifamily firm, RMR Group, for $80 million, and now splits his time between Los Angeles and Miami Beach.

Carroll was hit with an aggravated stalking charge in Tampa in November, and the following month, he was arrested in Wyoming for allegedly violating a 15-day restraining order from his ex-wife, Lindsey Truex. It was later determined that Carroll’s calls to Truex were made after the restraining order expired.

The multifamily investor also spent three days under involuntary psychiatric evaluation in March 2024 by order of Miami courts. A few days prior, law enforcement had responded to an emergency call about gunshots coming from his property. At that time, Carroll had also posted on Instagram a video of himself firing what he claimed were blanks from a shotgun while on a boat docked behind his Miami property.

Two of Carroll’s former security guards also sued him in LA County in recent months for wrongful termination, false imprisonment and a hostile work environment, alleging that Carroll held them at gunpoint and called them racial slurs. Carroll has denied the claims.

Email Lillian Dickerson

This post was originally published on this site

Chris Choi has been named Chief Financial Officer at MoxiWorks

Software company MoxiWorks has bolstered its C-suite with the hiring of Chris Choi as Chief Financial Officer. Choi was working on an interim basis prior to being formally named to the position.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the power of the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

Software company MoxiWorks has bolstered its C-suite with the hiring of Chris Choi as Chief Financial Officer. Choi was working on an interim basis prior to being formally named to the position, according to an April 28 statement.

TAKE THE INMAN INTEL SURVEY FOR APRIL

“After an extensive search, we found in Chris a leader with deep financial expertise and a proven ability to drive sustainable growth,” said MoxiWorks CEO Eric Elfman in the release. “His strategic insight and operational acumen will help MoxiWorks accelerate our transformation and solidify our position as an industry leader.”

With two decades’ tenure in startup environments, the release stated the CFO hasn’t been filled at MoxiWorks “in recent years” and that Choi’s integration “follows MoxiWorks’ recent capital raise and reflects the company’s ongoing momentum and commitment to long-term strategic growth.”

Choi was working at a company called Flash Array as its CFO, a business unit of publicly traded data storage company Pure Storage. He held the same position at Rescale, a B2B SaaS company backed by high-profile investors including Jeff Bezos, Sam Altman and Richard Branson. His early career was defined by work in investment banking with stints at ING Barings, Lehman Brothers, Lazard, and Barclays Investment Bank.

In October, MoxiWorks named Ben Tao as its first chief marketing officer and Jackson Mayes as chief of staff, Inman reported. The company’s leadership structure has changed within the last year, starting with Elfman replacing York Baur in June.

Staff updates have coincided with product updates. In September, MoxiWorks gave buyer agents a series of email and marketing tools to help them manage a fast-changing environment through solutions MoxiPresent and MoxiWebsites.

The recent capital raise came in January of this year from its existing parent group, as well as Vector Capital and brokerages Howard Hanna Real Estate Services and Windermere Real Estate. That money is being put to work to continue pushing creative, industry-leading product changes, the company said.

“This includes the development of expanded, modern capabilities that align with how agents work today, including an intuitive user interface that relies on AI and automation to streamline workflows and provide valuable insights that allow agents to work faster and smarter, and ultimately win more business,” the company said in January of this year.

“After two months at MoxiWorks, I’m more convinced than ever that the team’s vision is not just achievable, but an exciting challenge I’m eager to take on,” said Choi in the release. “With its strong market position, ownership structure and commitment to innovation, MoxiWorks is well-positioned for long-term success.”

Email Craig Rowe

This post was originally published on this site

Fewer consumers think it’s a good time to buy — or sell: Inman-Dig poll

Rapid fluctuations in tariff policies by the Trump administration have the economy and the stock market in a volatile state, which is weighing heavily on consumers, findings from the latest Inman-Dig Insights consumer survey, conducted in April, show.

This report is available exclusively to subscribers of Inman Intel, the data and research arm of Inman offering deep insights and market intelligence on the business of residential real estate and proptech. Subscribe today.

Americans have been dealing with uncertainty lately — and how they react to it may have a significant impact on the spring homebuying market.

Trump administration tariff policies have plunged the economy and stock market into uncertainty, a concern weighing heavily on consumers, according to the latest Inman-Dig Insights consumer survey. Among 3,000 Americans polled, 70 percent believe now is a bad time to buy a home, up 10 percent since January.

Americans were only beginning to grasp what “reciprocal” tariffs announced during the first week of April might mean for their wallets when, on April 9, the Trump administration announced it would pause the implementation of those tariffs for 90 days. The Dig Insights poll was conducted April 9-15.

TAKE THE INMAN INTEL SURVEY FOR APRIL

Growing worries over the potential surging cost of goods in response to tariffs, as well as expenses involved in homebuying, have more consumers thinking it’s a bad time to buy a home. The good news is, not all consumers are ready to completely throw in the towel when it comes to transacting, which is something agents may be able to latch onto.

Concerns over affordability

Americans are worried about high costs coming at them from all angles right now, whether it’s from housing or the rising prices of goods.

  • As of April, 17 percent of consumers polled said they felt inflation most significantly when it comes to housing costs, compared to 23 percent of consumers who cited housing costs as the biggest impact of inflation in January.
  • 67 percent of consumers polled in April said inflation was most significantly impacting them at the grocery store, compared to 56 percent of consumers in January.

The good news is that fewer consumers today feel the impact of inflation on housing, which has the potential to make them look more favorably on transacting. But, because consumers are also likely to prioritize buying groceries over meeting their homebuying goals, they may also be reserving more of their budget to go toward the rising cost of other goods now, which could potentially chip away at their buying power when it comes to a real estate transaction.

A larger share of consumers also now believe that average home prices and average mortgage rates will increase in the next year.

  • 57 percent of consumers in April said they believe average home prices will increase over the next 12 months, compared to the 50 percent who believed in January that home prices would rise in the next year.
  • 51 percent of consumer respondents in April said they think average mortgage rates will increase in the next 12 months, compared to 45 percent in January who said they think rates would rise during the same period.

Sentiment sours on homebuying; selling more stable

  • In April, 70 percent of consumer respondents said that it was a bad time to buy a home in the U.S., compared to 60 percent in January.
  • 30 percent of respondents in April said it was a good time to buy a home in America, compared to 40 percent in January.

Most consumers who feel it is a bad time to buy a house now cited unaffordable home prices (73 percent of respondents) and high mortgage rates (72 percent of respondents) as barriers to homebuying. Low inventory and difficulty in qualifying for a mortgage were also options that survey respondents could select in this “select all that apply” question.

About 4 percent of respondents (75 individuals) elected to write in a response to this survey question about why they felt it was a bad time to buy a home. Many of those respondents cited some version of market volatility, economic fluctuations, the Trump administration’s tariffs and the imminent threat of an economic recession or depression as reasons why it’s a bad time to buy a home in the U.S.

The responses reflect the intense anxiety and frustration a portion of Americans are experiencing right now and how it’s impacting their thoughts on transacting real estate.

Despite the distinctly negative responses around homebuying, consumers were less severe in their outlook on homeselling, though optimism was hard to find.

  • 61 percent of consumer respondents said in April that they thought it was a good time to sell a home in the U.S., compared to 65 percent in January.
  • Meanwhile, 39 percent of respondents said in April that it was a bad time to sell a home in the U.S., compared to 35 percent in January.

The difference in these responses shows the disconnect between buying and selling in the U.S. market today, which real estate agents will have to grapple with moving deeper into the spring market.

If Thursday’s existing-home sales report, which showed sales falling to their slowest pace since 2009, is a harbinger of what’s to come, agents will need to develop new strategies to pivot during this time of uncertainty.

About the Inman-Dig Insights Consumer Survey

The Inman-Dig Insights consumer survey was conducted from April 9 through April 15 to gauge the opinions and behaviors of Americans related to homebuying. 

The survey sampled a diverse group of 3,000 American adults, who ranged in age from 24 to 65 and were employed either full-time or part-time. The participants were selected to produce a broadly representative breakdown by age, gender and region.

Statistical rigor was maintained throughout the study, and the results should be largely representative of attitudes held by U.S. adults with full- or part-time jobs. Both Inman and Dig Insights are majority-owned by Toronto-based Beringer Capital.

Email Lillian Dickerson

This post was originally published on this site

Lesson Learned: Relationships matter more than anything

Learn how luxury agent Miltiadis Kastanis connects high-net-worth individuals with premier Miami Beach properties.

Bigger. Better. Bolder. Inman Connect is heading to San Diego. Join thousands of real estate pros, connect with the power of the Inman Community, and gain insights from hundreds of leading minds shaping the industry. If you’re ready to grow your business and invest in yourself, this is where you need to be. Go BIG in San Diego!

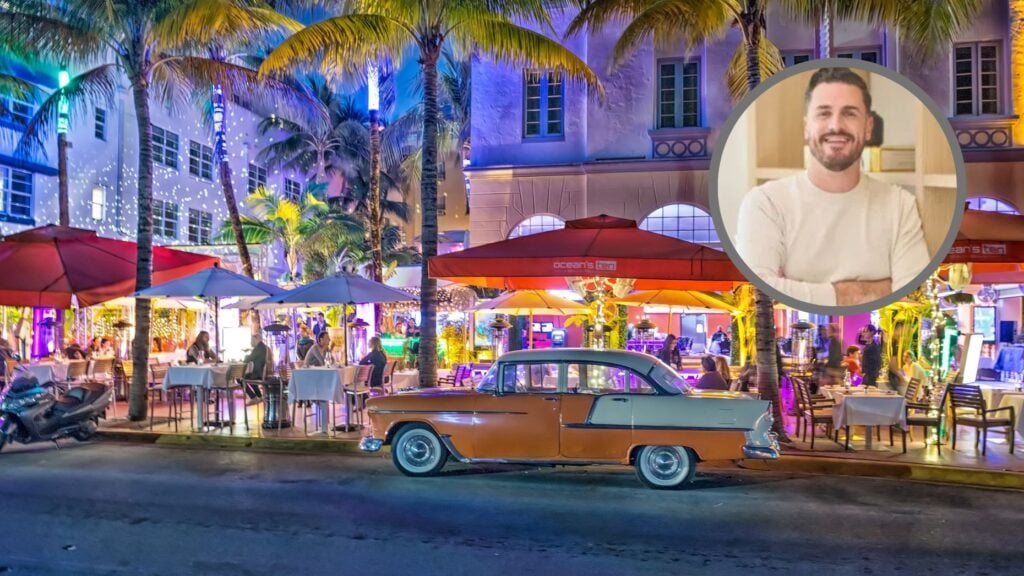
Luxury real estate specialist Miltiadis Kastanis thrives on selling new developments. “I love traveling to explore different cities, studying their buildings and homes to see how design and innovation evolve across the world,” he said.

Hailing from upstate New York, Kastanis made an impact immediately after entering the Miami Beach real estate scene in 2014, closing high-profile deals that captured media attention and built his reputation for delivering exceptional results with the sales of some of Miami Beach’s most iconic developments.

Learn how this luxury agent connects high-net-worth individuals with premier properties.


Name: Miltiadis Kastanis

Title: Director of New Development Sales

Experience: 11 years

Location: Miami Beach

Brokerage name: Compass

Rankings: Top 1 percent nationwide

Sales volume: $500 million

Awards: Top agent by volume, No. 4 agent by GCI in Florida


What’s the best advice you’ve ever received from a mentor or colleague? 

Real estate is a contact sport — relationships matter more than anything. Success in this business comes from building and maintaining strong connections.

What would you tell a new agent before they start out in the business?

The art of the deal remains the same, no matter the size of the transaction. Master the fundamentals, and you can navigate any deal with confidence.

What do too few agents know that would make their lives easier?

Delegate the tasks you don’t enjoy and focus on what you love. Playing to your strengths will make your business more efficient and fulfilling.

What’s one thing everyone should be doing to improve their life or business? 

Stay organized, and commit to a structured calendar. Time management is everything in real estate.

If you could do anything other than real estate, what would it be and why? 

If I weren’t in real estate, I would be an architect, without question. I’ve always been fascinated by the way spaces are designed and how architecture shapes the way people live and interact.

The creativity, precision and vision that go into bringing a structure to life are incredibly inspiring to me. Whether it’s a historic landmark or a cutting-edge modern masterpiece, I love studying the details, materials and functionality of great design.

This passion naturally translates into my real estate career, where I get to work closely with developers and designers, appreciating the artistry behind every home and building I sell.

Tell us about your most memorable transaction

Closing the penthouse at the W South Beach was unforgettable — especially when the buyer spontaneously jumped into the private pool during the showing!

Email Christy Murdock

This post was originally published on this site

Fair Housing Month is as crucial as ever — Zillow data shows why

April is National Fair Housing Month, a time to reflect on the progress made and the challenges that remain in ensuring equal housing opportunities for all. This month and every month, it’s crucial to address the systemic barriers that have historically hindered equal access to homeownership. Zillow is at the forefront of this effort, leveraging its extensive housing data to highlight existing disparities and promote fair housing practices.

Privately listed homes disproportionately harm sellers of color

Private listing networks harm buyers, sellers, agents and the industry at large. Zillow research shows in 2023 and 2024, home sellers who opted to sell off the MLS typically lost out on nearly $5,000, selling their home for 1.5 percent less than those listed on the MLS. The impact was particularly severe in communities of color, where homes sold off the MLS in these areas typically sold for 3.2 percent less than MLS-listed homes — more than double the 1.2 percent loss in majority white neighborhoods. Read more here

Boosting Black homeownership: Build more housing, improve credit reporting

Homeownership is a critical factor in reducing wealth inequality, particularly for Black households. Fewer than half of Black households own their homes, and the rapid rise in home values during the pandemic, coupled with a doubling of mortgage rates, has further strained housing affordability, keeping many potential Black homeowners on the sidelines. Addressing these disparities requires intentional policies and interventions that target the barriers keeping Black households from homeownership. Read more here

Hispanic homeowners narrow home value gap to smallest margin on record

Hispanic homeowners have made strides in narrowing the home value gap with white homeowners over the past two years, regaining ground lost during the pandemic. The gap is now the narrowest ever observed. However, while gradual progress is being made in closing the gap, the jump into homeownership remains a significant hurdle for Hispanics. According to Zillow’s 2024 Consumer Housing Trends Report, Hispanics represent 18 percent of prospective buyers, but 13 percent of successful purchasers. Read more here

How can agents use this data?

  1. Promote equitable access to listings: Advocate for equitable access to listings to ensure that all clients, particularly those in communities of color, have fair market opportunities and can achieve higher sale prices.
  2. Support affordability initiatives: Leverage data to support initiatives that improve access to down payment assistance, credit-building programs, and affordable housing construction, thereby helping clients overcome financial barriers.
  3. Stay current: Use Zillow’s commitment to promoting fair housing and its extensive research data to stay informed about market trends, advocate for policy changes, and provide clients with the most up-to-date information to guide their real estate decisions.

By shining a light on these issues, Zillow aims to foster a more inclusive and equitable housing market for everyone. For more insights and detailed reports, visit Zillow Research.

This post was originally published on this site