Central Park Tower’s priciest penthouse removed from market

Central Park Tower’s priciest penthouse removed from market

Central Park Towers: Priciest Penthouse Removed from Market
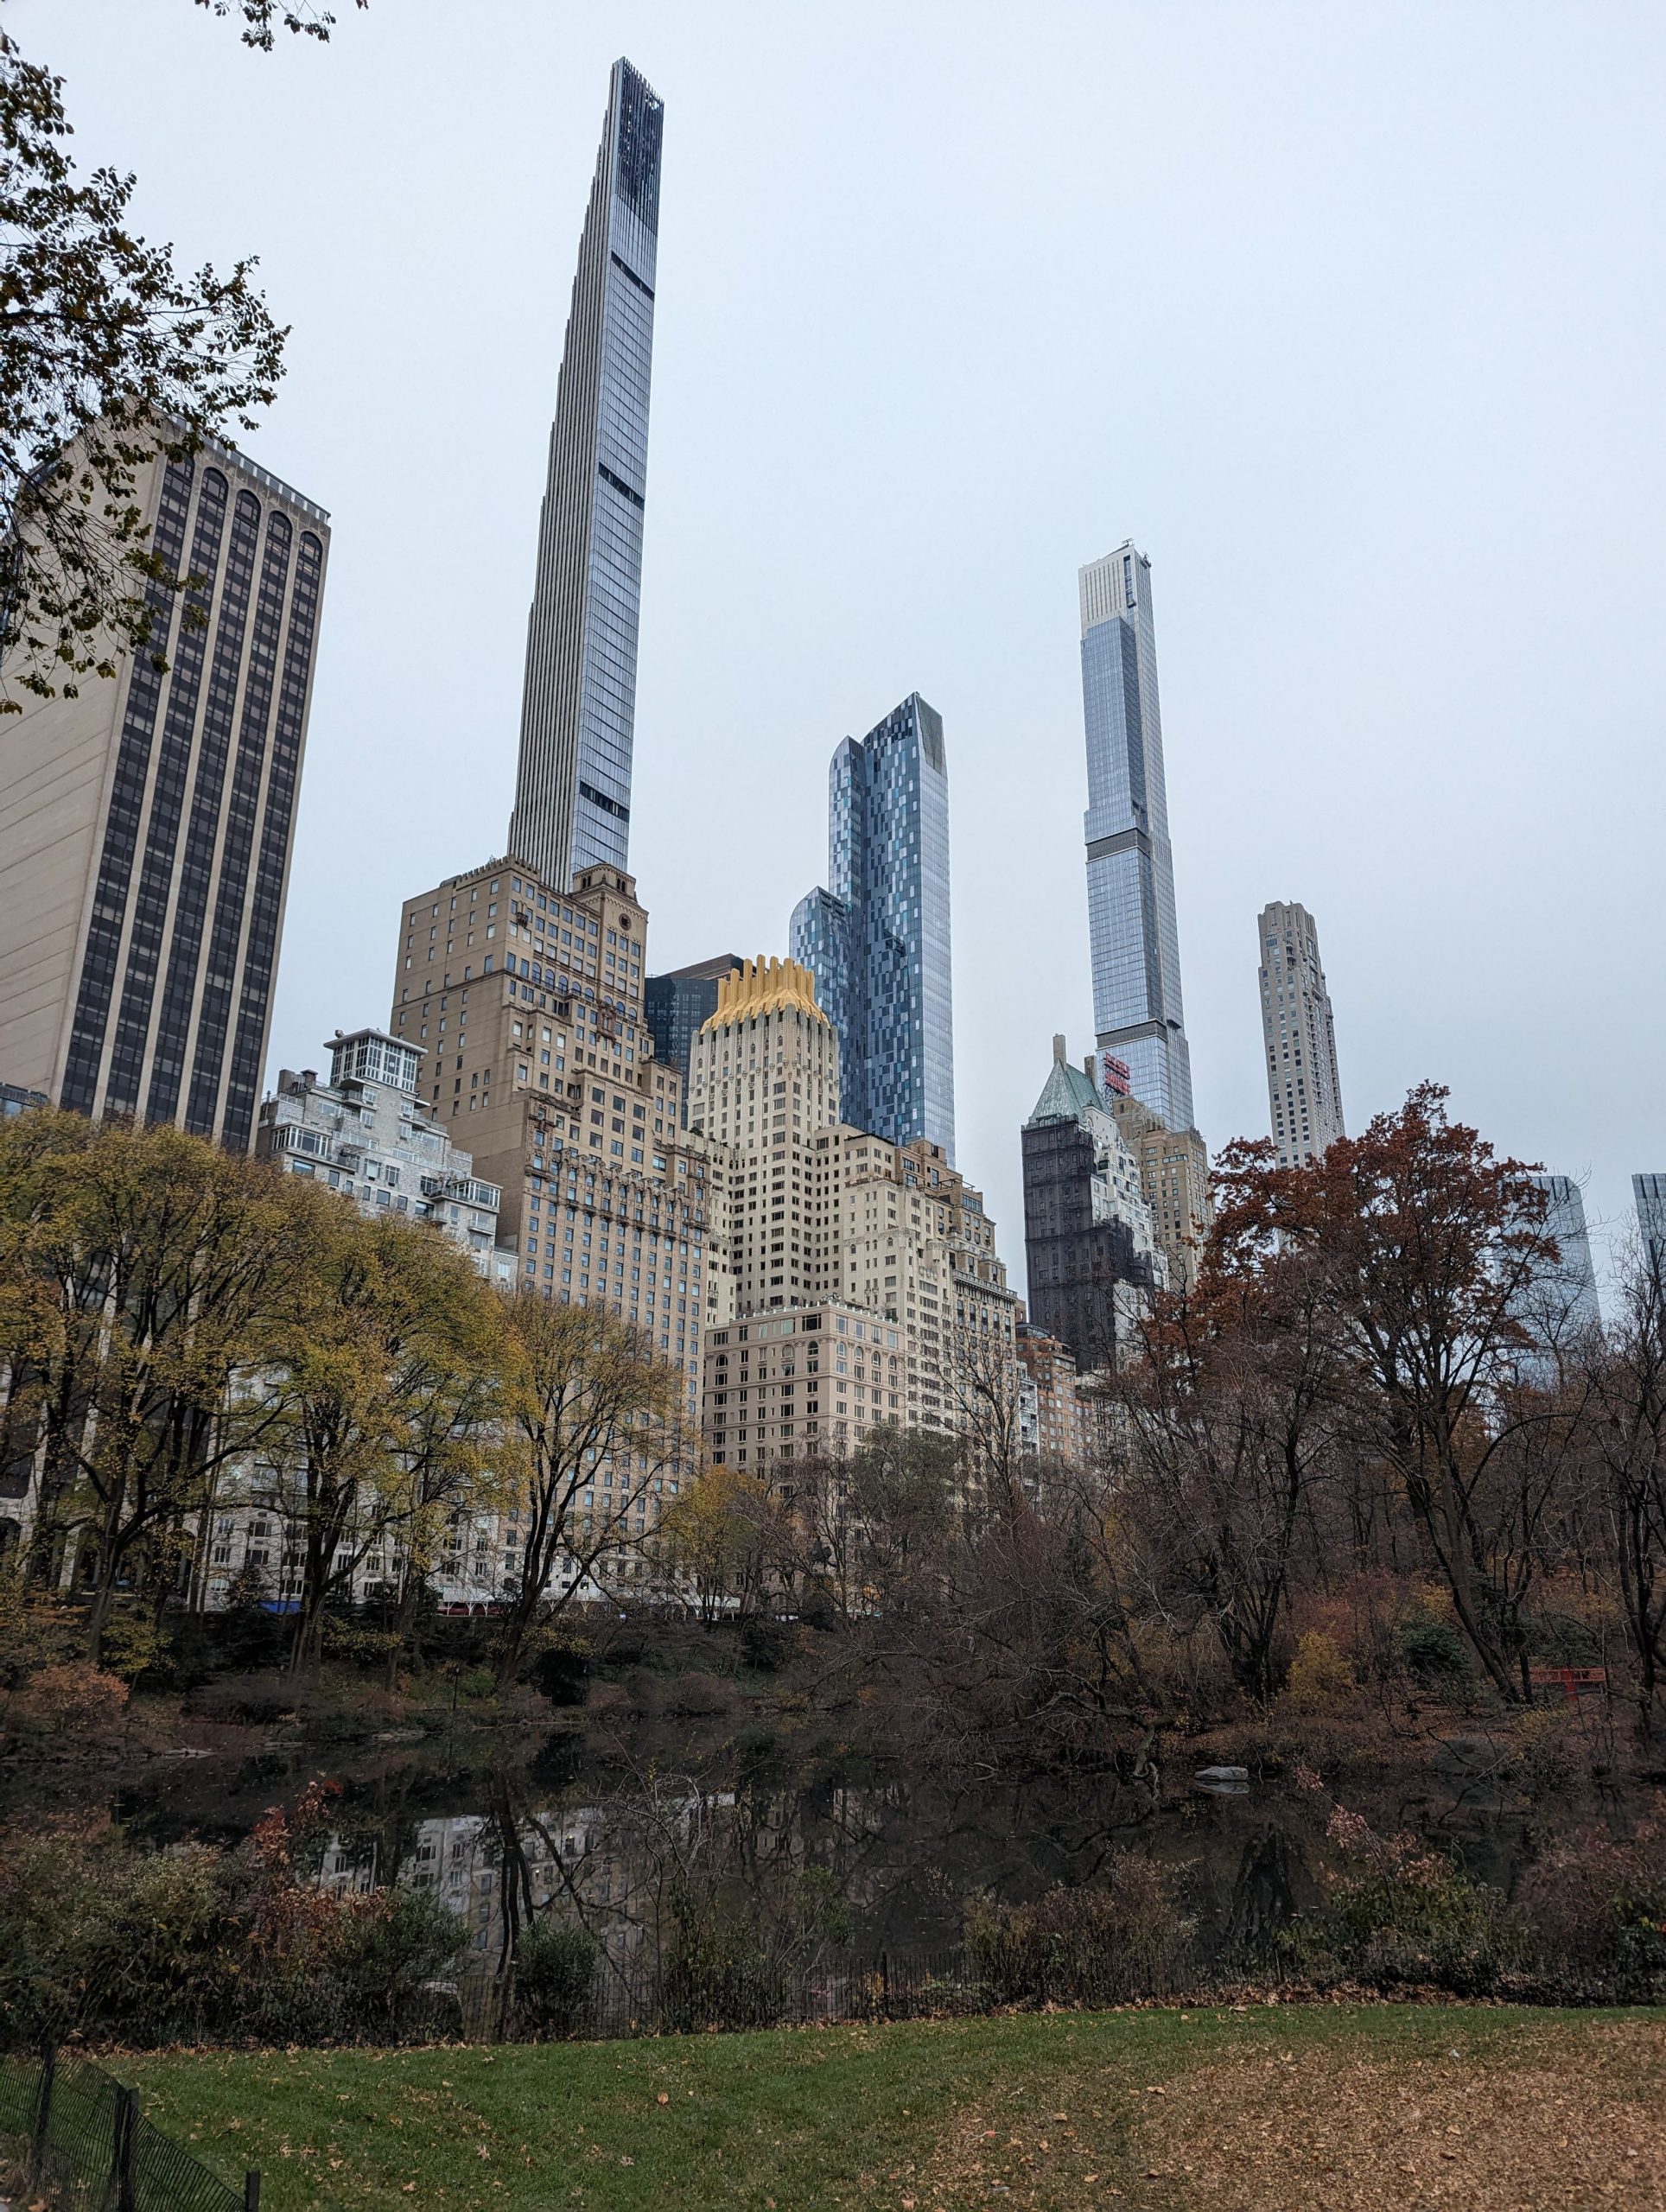
Photo by @ATHO&GOODLIFE: https://www.pexels.com/photo/skyline-of-manhattan-skyscrapers-in-fall-34976640/

The 17,500-square-foot triplex that once asked $250 million was heavily featured in Serhant’s new Netflix series, “Owning Manhattan.” It is unclear who will now rep the listing.

Inman Connect Las Vegas is LIVE this week! Get all your real estate questions answered and network with thousands of industry leaders. Join us virtually from anywhere in the world — the future of real estate is unfolding now.

One of the priciest penthouses to ever be marketed in Manhattan has been taken off the market, and it appears that listing broker Ryan Serhant is no longer repping the property, The Real Deal reported.

Extell Development’s penthouse at Central Park Tower, dubbed by SERHANT. marketing materials as “The One Above All Else” for its status as the tallest residential property in the world, asked a stunning $250 million when it first hit the market in 2022.

The 17,500-square-foot triplex was heavily featured in Serhant’s new Netflix series, Owning Manhattan, showing Serhant and some of his top agents beating the pavement in an attempt to sell the unit before the firm’s six-month contract with Extell expired.

In September 2023, the asking price on the unit was slashed to $195 million. As of the premiere of Owning Manhattan at the end of June, SERHANT. was still repping the property. About one week later, the penthouse was removed from the market.

Serhant was unavailable to comment to Inman, and Extell did not respond to a request for comment by press time.

When the property’s price was cut last fall, Extell founder Gary Barnett said the initial asking prices in the building were “headline prices” and the discount was made “to get serious” about selling the unit.

The penthouse’s delisting comes just weeks after another, lower-priced penthouse unit in the building sold for $115 million. Fredrik Eklund, John Gomes and Kent Wu of Douglas Elliman’s Eklund | Gomes Team brought the buyer. The deal marked the first New York City residential sale above $100 million since 2022.

During the second week in July, another $100 million-plus sale transacted when developer Vlad Doronin laid down $135 million for a penthouse at his own luxury condo conversion project at the Crown Building. In 2019, Doronin told The Wall Street Journal that an Asian investor agreed to purchase the unit.

In June, nine-figure deals started increasing in frequency across the country. By that month, the number of sales over $100 million nationwide had already surpassed the total of such deals closed in 2023, according to appraisal firm Miller Samuel.

Central Park Tower has yet another penthouse currently for sale with an ask of $150 million. Shlomi Reuveni of Reuveni Development Marketing and Christie’s International Real Estate Group are representing the listing.

Get Inman’s Luxury Lens Newsletter delivered right to your inbox. A weekly deep dive into the biggest news in the world of high-end real estate delivered every Friday. Click here to subscribe.

Email Lillian Dickerson

Succeeding in luxury real estate is all about storytelling

Panelists at Inman Luxury Connect Monday argued that good marketing in the luxury segment is all about telling stories that speak to a specific type of consumer.

Inman Connect Las Vegas is LIVE this week! Get all your real estate questions answered and network with thousands of industry leaders. Join us virtually from anywhere in the world — the future of real estate is unfolding now.

Early in his career, Jonathan Spears had to figure out how to market his stretch of Florida.

Spears works on the Florida panhandle and said on stage Monday during Inman Luxury Connect that eastern Florida, in a totally different time zone, has historically received much of the attention and traffic from higher-end buyers. His task as an agent, then, was to put his part of the state on the radar of people looking for second or third or fourth homes.

Then he hit on an idea: He started describing his region as the “Hamptons of Florida.”

“I knew that my luxury client base would gravitate to that,” he told the Connect audience.

The name stuck and soon began appearing in various media outlets. Today, the first result in a Google search for “Hamptons of Florida” is an AI-generated blurb pinpointing the exact area Spears covers. And Spears — who is with Compass — has since managed to grow his business into a thriving team that is effectively self-sufficient, in no small part because he has managed to effectively market his region.

Spears’ point, and his advice to the packed ballroom Monday, was that succeeding in luxury real estate involves “really understanding how to articulate the market’s story” in a way that connects with a desired audience.

From left to right, moderator Holly Meyer Lucas, Nancy Almodovar, Georgina Jacobson and Jonathan Spears at Inman Luxury Connect Monday. Credit: AJ Canaria

Spears’ fellow panelists Monday made similar points. Georgina Jacobson of Coldwell Banker works in Newport Beach, California, and told the audience that she recently redesigned her website. And her goal in the project was, essentially, storytelling.

“We focused on telling people about Newport Beach,” she said.

Later during the session, Houston-based Nancy Almodovar of Nan and Company Properties described how she uses social media in marketing and storytelling.

“We all use social media; it’s all about how you use it,” she said. “It’s very important that what you put out is what you want others to see.”

Almodovar said that her social media profiles are filled with images of real luxury properties in her market. But she cautioned that some agents are apparently tempted to present a false image, posting shots of luxury cars for example,  when they don’t own or sell those cars. She advised against such posts and indicated that authenticity matters when it comes to storytelling.

As the session concluded, Spears shared tips for winning media coverage, noting that he spends a lot of time meeting with journalists, and advised building relationships with the people who cover real estate. Having a great property can help facilitate those relationships.

“Having a marketable moment allows you to create relationships with a journalist,” Spears concluded. “The press loves to devour the biggest deals in the market.”

Email Jim Dalrymple II

New age in luxury: The rise of AI, social media and millennials

Luxury Connect panelists said that a generational wealth transfer is lifting more millennials into the luxury real estate market, and it’s already changing how luxury brokerages are working to attract clients.

Inman Connect Las Vegas is LIVE this week! Get all your real estate questions answered and network with thousands of industry leaders. Join us virtually from anywhere in the world — the future of real estate is unfolding now.

Evolving buyer profiles and advancements in tech are creating substantial opportunities for luxury brokerage operations, a panel of experts argued at the Inman Luxury Connect real estate conference Monday in Las Vegas. And while some luxury clients still prefer to keep a low profile, more clients than ever are coming from a generation of clients who grew up familiar with social media and are excited to see their listings featured in prominent, glitzy social media campaigns.

The luxury real estate sector is increasingly bringing high-dollar millennial buyers into the fold, and agents are making meaningful inroads with these clients by crafting high-end social media experiences.

However, this more tech-centric focus isn’t only about attracting a new generation of clients. Luxury agents and brokers are also taking advantage of generative AI and other advanced computing tools to streamline their operations, target consumers with ads and hone messaging in record time.

“We have to keep in mind that the transfer of wealth is going to the millennials — it’s going to the next generation,” Quiana Watson of Watson Realty Co. in Atlanta said. “And when you look at how they want to be treated and how they interact on social media, it is a big deal. So we can no longer operate real estate the way we used to.”

The transfer of wealth is likely to be staggering by some estimates, launching many younger adults into the thick of the luxury market who have not participated before.

Ranjeet Guptara, financial advisor at UBS | Photo by AJ Canaria Creative Services

UBS financial advisor Ranjeet Guptara told the audience of luxury real estate professionals that adults over the age of 75 control about a quarter of the nation’s wealth. As a result, it’s expected that $87 trillion of wealth will pass to younger generations in the next 10-20 years, Guptara said.

Some of the early effects of this transfer are already leaving a mark on luxury agents and brokers like Watson, Dawn McKenna of Coldwell Banker, Paul Benson of Engel & Völkers and Bryce Pennel of Douglas Elliman, who shared their on-the-ground experience with Inman Luxury Connect attendees.

The increasing benefits of reaching potential buyers and clients on social media come at a welcome moment when luxury brokerages can benefit from focusing more on marketing and less on lead generation, Benson said.

“I’m not a big fan of lead generation,” Benson said, “but I am a big fan of getting that home in front of the right people, wherever that is. And yes, you have to spend a lot of money to do it. But you also have to communicate that you’re doing it.

“So that’s where Instagram, I think, and other social media channels, come in to really make sure the client knows what you’re doing.”

Watson said she has folded her firm’s social media promotional muscle into her pitches to potential clients — something that younger clients in particular have been receptive to.

“I show them those markers of how my clients come back, the equity they’ve appreciated and how they’re able to continue on, but they’re going to have that social media experience,” she said.

Newer tech features — from ChatGPT to back-end AI solutions — have allowed Watson to save updating templates, reduce expenses managing her database and improve how she is able to reach potential clients with targeted ads, she said.

All that is being embraced by others in the industry, Benson said. However, they are not yet a substitute for good, old-fashioned communication with potential clients, he cautioned.

“The CRMs, the AI, the ability to do the virtual staging, ChatGPT not just for descriptions but for business plans — that’s all great,” Benson said. “But the telephone. I don’t think there’s been a time since I’ve done this in 20 years that clients had more questions about our industry.”

McKenna said she is spending hundreds of thousands of dollars on new tech lately. But like Benson, she’s continued to have success through old-school techniques as well, such as holding curated events at a luxury listing that help expand her database.

“It has really proved to be very fruitful in terms of results,” McKenna said of these event efforts.

And even in this age of social media — which Pennel said he has leaned into — much of his L.A. luxury business still comes from referrals. Relationships remain key to success at every level of real estate, he said.

Kitchen islands still reign supreme with homebuyers: Study

Remodeling marketplace Fixr’s 2024 home design survey revealed homebuyers are prioritizing organization and energy-saving features, alongside open and hybrid floor plans.

Inman Connect Las Vegas is LIVE this week! Get all your real estate questions answered and network with thousands of industry leaders. Join us virtually from anywhere in the world — the future of real estate is unfolding now.

Although all-white cabinetry, speckled granite countertops and subway tiles have fallen from grace, there’s one thing today’s homebuyers can’t get enough of: kitchen islands.

TAKE THE INMAN INTEL INDEX SURVEY FOR JULY

In remodeling marketplace Fixr’s 2024 home design survey, 61 percent of homebuilding and remodeling experts said kitchen islands are homebuyers’ most-requested feature, followed by walk-in pantries (43 percent), laundry rooms (31 percent), patios (30 percent), hardwood flooring (28 percent) and multi-zone HVAC systems (28 percent).

Full bathrooms on the main level, solar panels and landscaping, and Energy Star windows rounded out the top 10, with a fourth of experts saying those features made a home more desirable. The survey didn’t discuss the return on investment of these features; however, a 2019 Zillow study said minor kitchen updates — such as installing a new island — provide an ROI of 81.1 percent.

“A kitchen island has many perks, improving both the look and usefulness of your kitchen, as well as allowing bar seating,” the Fixr survey read. “It gives you extra countertop space for cooking and prepping meals, making things more efficient and organized.”

“Plus, with built-in storage options, an island helps keep your kitchen tidy by providing additional cabinets and drawers,” it added. “This makes sense considering 83 percent of experts said storage was the biggest kitchen priority in 2024.”

After kitchen islands, walk-in pantries are the second most coveted feature as they keep over-counter cupboards from becoming cluttered and offer additional food storage space.

“Continuing the theme of storage as a must, walk-in pantries are set to impress home buyers when looking around a potential new home this year,” the survey explained. “With its spacious design, a walk-in pantry helps reduce clutter by providing plenty of shelves and storage options. It gives you ample space to store food and kitchen supplies, keeping everything neat and easily accessible.”

Beyond features that maximize storage and organization, such as a dedicated laundry room and fully covered patio, professionals said buyers desire energy-saving features that reduce utility costs. The top eco-friendly feature homebuyers want is a multi-zone HVAC system, which enables homebuyers to set separate temperatures for each part of their home.

“It allows for precise temperature control in different areas or rooms, ensuring everyone stays comfortable. By only heating or cooling the spaces in use, a multi-zone system can reduce energy consumption and lower utility bills,” the survey read. “A multi-zone HVAC system enhances overall climate control, making your living environment more pleasant year-round.”

Beyond storage and energy management, Fixr’s survey respondents said homebuyers still favor open floor plans (53 percent). Hybrid floor plans (47 percent) are gaining traction as well since they give buyers access to the flow of an open floor plan with several dedicated closed spaces.

“Hybrid floor plans are great, as you get the benefit of open space (larger rooms, connectedness), but also the opportunity to provide for quieter moments, perhaps with a separate dining room or TV room that has doors,” Lewis Schoeplein Architects Principal Toni Lewis told Fixr. “This seems to be where many families have landed on the ‘ideal’ floor plan.”

Email Marian McPherson

Commercial market bottom nears as foreclosures surge

Portfolios of foreclosed and seized office buildings, apartments and other commercial buildings hit $20.5 billion during the second quarter of 2024, the highest quarterly figure posted since 2015, according to MSCI.

Inman Connect Las Vegas is LIVE this week! Get all your real estate questions answered and network with thousands of industry leaders. Join us virtually from anywhere in the world — the future of real estate is unfolding now.

After years of post-pandemic struggles, the commercial property market may at last be near-bottom after a quarter in which foreclosures hit their highest rate in nearly a decade.

TAKE THE INMAN INTEL INDEX SURVEY FOR JULY

Portfolios of foreclosed and seized office buildings, apartments and other commercial buildings hit $20.5 billion during the second quarter of 2024, according to data provider MSCI’s Capital Trends most recent report. That figure is 13 percent higher than Q1 2024 and the highest quarterly figure posted since 2015.

The commercial market has seen a rise in defaults and other distress in recent years as a result of the slow return of office workers and rising interest rates. Despite those rising numbers of defaults, lenders have held off on taking over properties, hoping that a recovery was in sight — and that they could avoid expensive foreclosure actions.

“Lenders will do everything in their power to avoid that,” Keefe, Bruyette & Woods analyst Jade Rahmani told The Wall Street Journal.

An increasing number of lenders have determined that office buildings may never recover their previous values, even after rates decline, which is leading to more foreclosures and short sales.

Commercial property values could continue to decline if the U.S. goes into a recession, causing companies to start laying off workers and, therefore, require less office space.

Based on similar spikes in foreclosures during previous downturns, market bottom may be close at hand. Lenders typically sell properties shortly after seizing them, which helps determine market value after extended periods of inactivity.

Offices have been hit the hardest, with the volume of office property seized through foreclosures and other actions up by $5 billion year over year, according to MSCI. Meanwhile, apartment buildings, which have also suffered amid high interest rates and growing supply, saw an increase of $975 million in portfolio volume seized since the second quarter of 2023.

A number of high-profile commercial properties have been seized as of late, including a five-building Silicon Valley complex owned by a venture of Goldman Sachs and TMG Partners, which was taken over by KKR Real Estate Finance Trust. KKR held a $200 million mortgage on the property and took title at the end of June in a deed in lieu of foreclosure transaction. The trust is expected to start marketing the complex shortly after making upgrades.

In Washington, D.C., where the office market has struggled, several buildings have sold at steep discounts. State Farm Life Insurance recently made a foreclosure sale of an office building just blocks from the White House. The property sold for $17.6 million, which was a roughly 70 percent discount from the owner’s original purchase price in 2010.

According to developer Matt Pestronk, who has purchased two discounted office buildings in D.C., “Lenders are more dispassionate about values, and that’s a sign of a cycle moving” toward bottom.

Small banks with fewer assets (especially under $10 billion) have adopted foreclosures at a quicker clip. The total value of seized commercial properties these banks owned during Q1 rose by roughly $125 million from the previous quarter to $943 million, the largest quarterly spike since 2000, bank data consultant Matthew Anderson told The WSJ.

Even if the Fed begins to cut interest rates in the fall as analysts anticipate, the commercial market is expected to take a long time to recover — and some office buildings may never recover their lost value. The sector’s risk will extend “probably for years,” Fed Chairman Jerome Powell said in a Senate testimony earlier in July.

Regulators are concerned about that prognosis for the industry because of the implications it could have on the financial system at large. More than $2.2 trillion in debt maturities are expected to come due between now and 2027, according to data firm Trepp.

Signature Bank’s failure last year serves as an early sign of what may come for other banks that have a high exposure to commercial property.

Investors have pumped cash into other banks holding vast quantities of commercial loans in order to stave off such failures, including First Foundation and New York Community Bancorp. On Thursday, the latter’s shares dropped more than 3 percent after disclosing another quarterly net loss.

Another foreboding sign is the increase in problem loans that many creditors are facing, including Blackstone Mortgage Trust (which has a large exposure to office loans). Last week, the company cut its dividend and increased loss reserves by 19 percent to over $900 million.

The delinquency rate of office loans converted into securities also jumped by 8 percent this month for the first time since November 2013, according to Trepp.

Despite growing concerns in the market, the number of foreclosures and other property seizures are still well below those seen during the 2008-09 financial crisis. In 2013, the number of foreclosed and seized properties held by lenders surged to more than $45 billion, more than twice the current rate, according to MSCI.

Since building owners have been more willing during this downturn to walk away from properties than in the last financial crisis, foreclosure figures may not ever reach the level seen during that time. At that time, owners wanted to hold onto low interest rates and hoped for a recovery.

“This cycle, a lot of investors believe office values are challenged,” Nicholas Seidenberg of real estate investment banking firm Eastdil Secured told The WSJ. “They’re saying: ‘Hey, I’m going to just walk away and not fight.’”

Email Lillian Dickerson

Bulletproof Ohio home goes under contract after multiple offers

The home was first listed for $399,900 over two weeks ago. Listing agent Jon Modene refers to it as having “the strangest and greatest potential I have ever seen.”

Inman Connect Las Vegas is LIVE this week! Get all your real estate questions answered and network with thousands of industry leaders. Join us virtually from anywhere in the world — the future of real estate is unfolding now.

An unusual, bulletproof Ohio home, left as part of the $54 million estate of the late Trudy Stranahan, is now under contract after multiple offers, the New York Post has reported.

Jon Modene of RE/MAX Masters has the listing.

The home was first listed for $399,900 over two weeks ago. Modene refers to the home as having “the strangest and greatest potential I have ever seen” — not surprising given the property’s features or lack thereof.

The single-family home sits on a 5.08-acre lot with $100,000 worth of fencing and over $300,000 worth of concrete. The property is windowless, and although there is no security system, every surface of the home is covered in Lexan, a material said to be both bulletproof and fireproof.

Modene told Realtor.com that the home is located in a low-crime neighborhood.

According to the New York Post, Stranahan belonged to the prominent family who founded the Champion Spark Plug Company in Toledo, Ohio. Stranahan spent much of her time alone at the compound, as she was said to have had no children, friends or pets.

The compound, located at 1360 Old Trail Road in Maumee, Ohio, was built by architect Ralph J. Copper in 1953. Prior to her death from cancer in 2023, Stranahan poured thousands of dollars into the compound. She left behind a $54 million estate.

In a statement to the New York Post, Modene stated that the home stands on an “amazing lot,” with perks including a “private shared lake.”

The compound stands right outside of Toledo, Ohio, on Silver Lake, bordering Metropark. The home itself stretches 3,355 square feet with three bedrooms and two bathrooms, one of which is mirrorless. Other features include two outbuildings, one of which is a spacious home gym where Stranahan spent most of her time.

There was also an Olympic-sized backyard swimming pool that Stranahan had filled in.

Modene told Realtor.com that many of the people who expressed interest in the house said they would likely tear it down or remodel it upon purchase.

Email Richelle Hammiel