by Amanda Neely | Aug 14, 2024 | Industry, News Feed
Learn how NYC agent Maggie Kent leverages her sense of professionalism to develop a higher level of client trust and how she has developed resilience to navigate the ever-changing world of real estate.
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
Top producer and star negotiator Maggie Kent has made a name for herself as a featured agent on HGTV’s hit Selling New York for seven seasons and a featured real estate expert in publications including The Wall Street Journal and The New York Times.
Kent’s family real estate firm won numerous awards in Canada, offering boots-up market insight, experience and client service expertise, combined with her own background in the arts, her creative sensibility and her marketing savvy.
Learn how she leverages her sense of professionalism to develop a higher level of client trust and how she has developed resilience to navigate the ever-changing world of real estate.
Name: Maggie Kent
Title: Associate broker at CORE, sales team at Eastlight Condominiums
Experience: 20 years
Location: New York
Brokerage: CORE Group Marketing
Sales volume: $850 million career sales
What would you tell a new agent before they start out in the business?
Real estate can be a very emotionally rewarding and lucrative career, but too many people enter into it thinking it doesn’t take much work to get started. The days of real estate existing as a side hustle are long gone, and it’s important for new agents to recognize that real estate is a full-time job and that these first years are crucial.
From building your clientele to getting listings to working with sellers, these things take time, energy, effort and strategy.
Find a great mentor who can guide you through as you build your career, stay up to date on market trends and pricing, and never be afraid to ask questions.
What do clients need to know before they begin a real estate transaction?
Being realistic about the financial requirements is paramount. For buyers, obtaining pre-approval for a mortgage is a crucial first step. This not only provides a clear picture of what they can afford but also strengthens their position when making offers.
It’s important for clients to account for additional costs beyond the purchase price of the property. This includes closing costs, property taxes, insurance, maintenance and any potential renovation expenses. Buyers should also consider the costs associated with moving and setting up their new home.
Perhaps most importantly, buyers and sellers need to know that while it’s important to be prepared financially, it’s equally important to be prepared mentally. Real estate transactions can be emotionally charged and stressful — there may be challenges and delays, so maintain a level-headed approach throughout the process.
Having a support system, whether it’s friends, family or, of course, a great real estate agent, can help manage the emotional aspects of the transaction.
What do too few agents know that would make their lives easier?
Realistic pricing — and remaining confident in your pricing — is key to a successful business. I was working on a new development in NYC in 2019; we priced everything according to market comps and felt confident in our choice.
Then COVID hit and the market went haywire. While other projects were offering extreme concessions for property, we remained steadfast in our pricing, offering no concessions, and were still able to sell the building out during COVID.
The same is true for my current project at Eastlight in Manhattan’s Kips Bay. We’ve seen significant success with the project, and realistic pricing based on market projections is core to that success.
What is the one thing everyone should be doing to make their life and business better?
Work-life balance. Our work tends to take over since we are independent contractors — you eat what you kill. As such, burnout is common in our industry, so planning and blocking out time to rest, recharge, and spend time with family and friends will help you maintain your sanity. As a result, you’ll be more efficient and build a longer-lasting, sustainable business.
If you could do anything other than real estate, what would it be?
I would be a doctor, specifically with Doctors Without Borders. It becomes clearer and clearer to me as I progress through my life that health is the most important aspect of every living thing. If I really had the capacity to be a doctor, I would love to help someone heal. I can’t think of anything more noble or important than that.
Email Christy Murdock
by Josh Ries | Aug 14, 2024 | Industry, News Feed
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
Pulse is a recurring column where we ask for readers’ takes on varying topics in a weekly survey and report back with our findings.
The heat is on, and a lot of people are getting geared up, stressed out and hunkered down in preparation for the Aug. 17 deadline for the implementation of terms of NAR’s commission suit settlement. Hopefully, at this point, you’ve got your paperwork on point; your buyer and seller consultations polished; and your mindset elevated so that you can answer questions for colleagues, mentees and clients.
via GIPHY
We know you’ve got big feelings, and we want to give you a place to vent anonymously: Tell us what’s on your mind this week. Are there things you’re still confused about? Concerned about? Angry about? Is your broker a big help, and is your association a source of helpful information? Where are you getting clarity, and what are the sources of ongoing confusion? Let us know below:
We’ll compile a list of the top responses and post them on Inman next Tuesday.
by Melanie Klein | Aug 13, 2024 | Industry, News Feed
After unsuccessful negotiation attempts with Oren and Tal Alexander, Chief Growth Officer Nicole Oge, CEO Richard Jordan and President of New Development Andrew Wachtfogel are “forfeiting ownership” of the firm.
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
After months of disruption at Side-backed firm Official in the wake of rape allegations levied against co-founders Oren and Tal Alexander, the firm’s other three co-founders have relinquished their ownership and are leaving the firm, Business Insider reported.
Chief Growth Officer Nicole Oge, CEO Richard Jordan and President of New Development Andrew Wachtfogel are “forfeiting ownership,” they told the news outlet, and effectively leaving operations of the two-year-old brokerage in the hands of the Alexander brothers.
Both Oren and Tal are now unlicensed in Florida and New York, their primary markets. They have denied the allegations against them, which have been detailed in multiple lawsuits launched by women who allege rape and sexual assault by the brothers dating back to at least 2010.
In a joint statement from Oge, Jordan and Wachtfogel that was emailed to Inman, the partners said the fallout from the rape allegations against Oren and Tal has seriously hindered the business.
“Since we first became aware of the accusations against Official’s other co-founders beginning in early June, we have worked to support our team and preserve the company on behalf of its employees, agents and clients,” the statement reads. “However, the impact of this news on our business has been severe. We work with the best people in the industry, but these events have significantly limited the ability of our agents and development teams to operate and transact with clients, and we anticipate future challenges that cannot be overcome.”
The trio’s departure will be effective on Aug. 15, 2024. The moves reportedly come on the heels of weeks of negotiations between the Alexander brothers and the other co-owners over ownership stakes in Official.
In a separate statement sent to Inman, Oge said she, Jordan and Wachtfogel had poured their “heart and soul” into the company, which had been moving on a successful path until the rape allegations against the brothers and their other brother, Alon Alexander, came to light.
“We made a huge impact in a short amount of time and are so proud of the work we did together,” Oge said. “We could not be more disappointed that we were not informed by Tal and Oren of these lawsuits and threats to our firm, and that our talented teams are now prevented from continuing Official on its path. These allegations are disturbing to us all, but importantly they are clearly opening up dialogue around the brokerage industry’s culture toward women at large.”
The news appeared to be in conflict with previous reports that suggested Oren and Tal were distancing themselves from Official after they had both publicly stated they would relinquish their roles as co-founders due to the lawsuits that had been launched against them.
However, their attorney, James Cinque, told Business Insider otherwise. He told the news outlet that the brothers “never said they were going to leave” and that “they want to continue with the business.”
“Official is concluding ownership and management changes to ensure continued excellent service to its markets,” Cinque said in a statement. “Tal and Oren Alexander wish the three members who are departing to pursue new opportunities the best of luck and much success. The Alexander brothers are excited about their new lineup and will be announcing details very soon.”
A representative for Tal Alexander did not immediately respond to Inman’s request for comment.
A spokesperson for Side told Inman that Tal and Oren’s real estate licenses are “not active on the Side platform.” They added that the firm “would not have established a partnership with them had we known of these serious allegations.”
Within one week of lawsuits against Oren and his twin brother, Alon, coming to light in June, Oge had said in a statement that Oren was “immediately isolated from the business” and that “the process of removing him from ownership is well underway.”
After Tal had later been accused of rape through a lawsuit filed in June, he said he would “take a leave” from Official.
Last month, Official West Coast founding agent Tyrone McKillen departed the firm along with his eight-person team, Plus Real Estate.
Within the last week, at least five agents in New York and Florida have also left the firm.
Oren has now been named in four lawsuits against him alleging rape and sexual assault, while Tal has been accused of rape in one lawsuit. Before the brothers co-founded Official, they were agents at Douglas Elliman for about 10 years.
Get Inman’s Luxury Lens Newsletter delivered right to your inbox. A weekly deep dive into the biggest news in the world of high-end real estate delivered every Friday. Click here to subscribe.
Email Lillian Dickerson
by Justin Ziegler | Aug 13, 2024 | Industry, News Feed
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
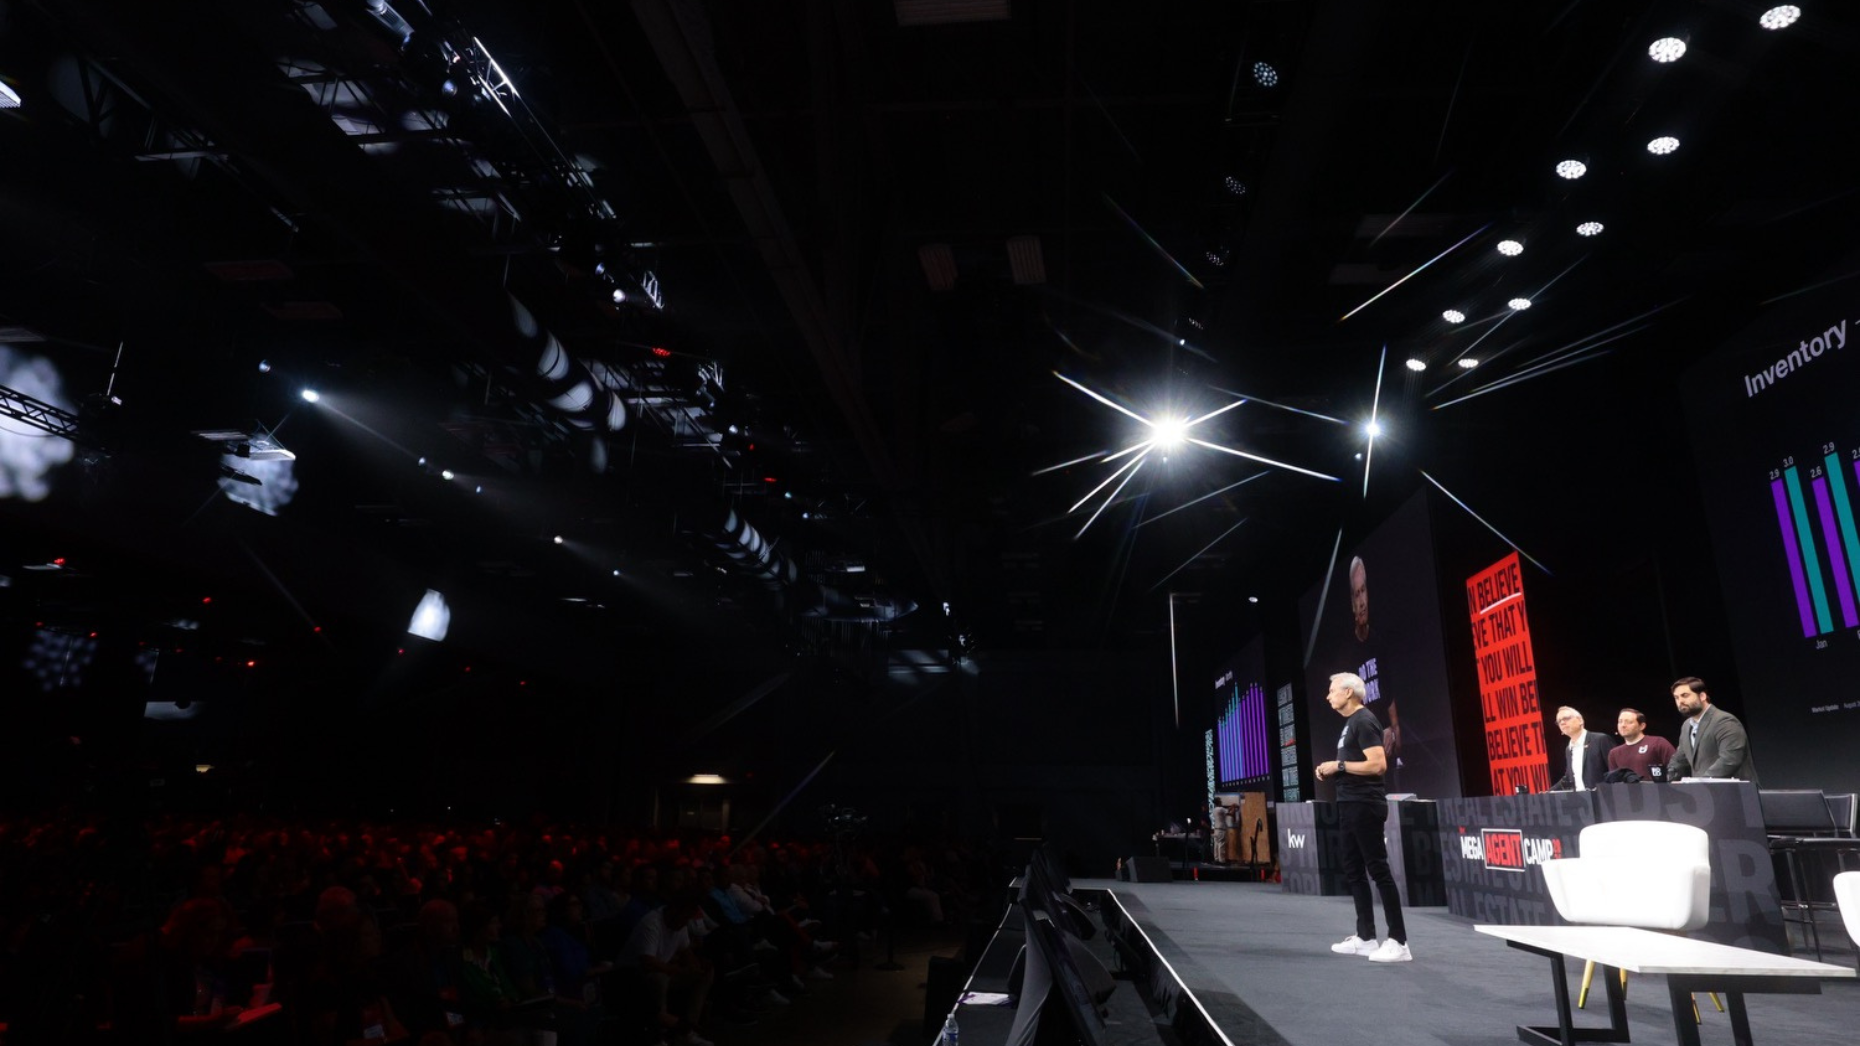
Recession fears have intensified over the past several months as Americans crack under the weight of a higher cost of living, elevated interest rates, and a slight uptick in unemployment and underemployment rates. Although economists have embraced the idea that the U.S. is in more of a “vibecession” than an actual recession, Keller Williams founder Gary Keller said that’s not the case for the real estate industry.
“Look, we’re already in a freaking recession in our industry,” Keller told 4,700 agents during the franchisor’s annual Mega Agent Camp conference on Tuesday. “What are you talking about? Well, you realize that you fundamentally are the only group in the United States right now and Canada that is in a recession. Your industry is. The rest of the economy is not in a recession.”
Keller, VP of Content Strategy Jay Papasan, Head of Industry and Learning Jason Abrams, and Chief Economist Ruben Gonzalez said the U.S. economy is in a precariously solid place, as the gross domestic product (GDP) reaches an annual average of 2.1 percent and the Consumer Price Index (CPI) inches closer to the target of 2 percent. However, the unexpected rise in unemployment rates to 4.3 percent has cast a wide shadow on the U.S. economic outlook.
“By the way, the Fed now looks up and says, ‘Hang on a second. We want four [or] less. This looks scary to me,’” Keller said. “So when they talk about recession, remember recession is people [spending] less money. People who are unemployed spend less money. Okay. So the more people you have that are unemployed, the less collective spending there is in the marketplace.”
Beyond unemployment rates, Gonzalez said current Treasury rate trends signal the economy is at the highest recession risk in nearly 45 years.
“In the past, any time the Treasury yield curve is inverted, it’s predicted a recession,” he said. “Based off of yields on Treasuries, the probability we have a recession is at the highest it’s been right now since the 1980s.”
As the U.S. inches closer to a potential recession, Keller and his crew said real estate has been in a “solo industry recession” with eight months of consecutive negative growth — two months more than the widely accepted benchmark for recessionary status. However, a series of anticipated rate cuts by the Federal Reserve is poised to bring real estate out of that recession in 2025.
Gonzalez and Keller said a drop in rates is exactly what real estate has been waiting on as homebuyers seek to regain some of the buying power they’ve lost in the face of rising rates and home prices. A drop in rates would also offer freedom for homesellers who’ve feared letting go of a sub-3 percent rate for a mortgage with a rate of 7 percent or more.
“You’ve been waiting for that,” Gonzalez said. “We’ve been waiting for them to come around to the idea, right, that what we have is a shortage of houses, right, and not an oversupply of buyers.”
Although dropping mortgage rates is a large part of the equation, the panel said affordability needs to improve as well. Keller said the trendline for median home price growth is 4 percent. If the market were on the trendline, the median home price would be $357,000. However, median home prices are $427,000 — 19 percent above trendline growth.
Gonzalez and Papasan said median home price growth is moving towards the trendline, but it’s yielding wildly different experiences for agents and consumers in different markets. In some markets, like Austin, new listings are booming and home prices are coming down. Meanwhile, in others, listings are stagnant and prices are sticky.
“It really becomes the tale of a bunch of different markets,” Papasan said.
Abrams and Keller said the solution to inventory and affordability issues is largely local, as city legislators can craft zoning plans that bolster the level of single-family and small multifamily (e.g., duplex, triplex, fourplex) housing. The federal government also has an important role, as evidenced by the Biden-Harris Administration’s plan to take unused federal lands and reallocate them for affordable housing developments.
“By the way, if you want to be a real estate professional, go down and start talking to your council members, your mayor, and start getting in their ear that if they want to solve affordability in their town, they need to quit waiting for the national interest rates to solve the problem,” Keller said.
All four men said the agents have no control over most market dynamics; however, they can “zoom in and zoom out” on those dynamics, help consumers navigate challenges with greater dexterity and make sales.
“I have a different perspective than a lot of you, and my perspective is shut up and get to work,” Keller said. “We have a ton of people coming across this stage today and tomorrow who are crushing it, who are outperforming the market. They’re unbelievable what they’re doing … There are plenty of homes being sold. There are more than enough home sales in your market for every one of you to hit your goals if you do the right things.”
Outside of mastering the basics, the panel said agents will need to adjust to upcoming changes in commission procedures, per the National Association of Realtors’ buyer-broker commission settlement.
Abrams urged agents to eschew commission advice they see on social media and rely on their brokerage and MLS leaders to help them comply with the new rules. He reminded agents about the details around marketing cooperative compensation and crafting buyer’s representation agreements, noting that agents should stay away from workarounds.
“MLSs are working through these changes, and they’re going to be implemented, and what best practices will emerge still remain to be seen,” he said. “Many opportunists and you see this every day on social media; they’re going to jump in and make quick conclusions and provide their opinions disguised as knowledge. Please be aware of that.”
“Just remember, real estate agents got a pass on the first one,” Keller added. “Almost a billion dollars was paid on your behalf. The second one, you won’t get a pass. Just be aware of that. The next time, if you violate the law, you’re on your own.”
After warning agents, Keller advised them to lead with transparency. If they do that, he said, the commission will take care of itself.
“When you hear all this hoopla and all of this really scare tactics, to be candid with you, there’s a lot of people that want to make money on the back of trying to scare you,” he said. “Is this a big change? Yeah. It is a big change in that it’s now transparent, and the buyer has to decide what they’re going to pay their agent. Yes. That’s a big change.”
“Does it affect how much you get paid? That’s going to be up to you,” he added.
Despite market and legal challenges, Keller and the panel said the real estate market is still headed for a coming boom and reminded agents that they should be proud of the work they do.
“You should be damn proud to be real estate agents, and what you do really matters,” Abrams said.
Email Marian McPherson
by Jill Butler | Aug 13, 2024 | Industry, News Feed
The “Prefab Hiking House” series of homes designed by OneSpaceHub includes a split-level 40-foot property featuring a sun deck for $48,000 and a single-story home with a terrace priced at $19,000.
Whether it’s refining your business model, mastering new technologies, or discovering strategies to capitalize on the next market surge, Inman Connect New York will prepare you to take bold steps forward. The Next Chapter is about to begin. Be part of it. Join us and thousands of real estate leaders Jan. 22-24, 2025.
Better known for books and appliances, online retailer Amazon has rolled out a trio of new tiny homes for sale — including a terraced model for $19,000 — in the face of rising property costs and sagging affordability.
The “Prefab Hiking House” series of prefabricated, compact homes features a 40-foot home with two levels and a sun deck priced at $48,000; a single-story build with a terrace priced at $19,000; and a similar model without a terrace priced at $16,570. Each is priced well below that of the typical home.
OneSpaceHub is the manufacturer of the latest tiny homes to hit Amazon, the New York Post reported Monday. The 5,000-pound home can be shipped in a month’s time, and is easy to assemble and relocate.
Though the home provides comfortable living, it was built for sustainability, according to the Amazon listing. The eco-friendly home was constructed with durable stainless steel and aluminum materials meant to minimize environmental impact.
The home features a customizable living space and outdoor space. Other features include a rooftop deck (depending on the selected style) and a functional kitchen and bathroom.
No customer reviews are available for the space yet, but the listing indicates that the home is ideal for couples or individuals interested in living off the grid or for outdoor adventures such as hiking.
Tiny homes have grown in popularity since the coronavirus pandemic, particularly in areas where zoning law have been updated to allow for accessory dwelling units (ADUs).
It is projected that the tiny house market will grow significantly in the years ahead, reaching $28 billion by 2031.
Email Richelle Hammiel
by Terry LeClair | Aug 13, 2024 | Industry, News Feed
WASHINGTON (August 13, 2024) – Almost 90% of metro markets (199 out of 223, or 89%) recorded home price gains in the second quarter of 2024, as the 30-year fixed mortgage rate ranged from 6.82% to 7.22%, according to the National Association of REALTORS®’ latest quarterly report. Thirteen percent of the 223 tracked metro areas experienced double-digit price gains over the same period, down from 30% in the first quarter. The median single-family existing-home price for the San Jose, California metro area was $2,008,000 – it’s the first time since NAR began tracking metro area single-family home prices in 1979 that a metro area’s median price exceeded $2 million.
“The record-high home prices in most metro markets bring good and bad news,” said NAR Chief Economist Lawrence Yun. “It’s terrific news for homeowners who are moving ahead in wealth gains. However, it’s difficult for those wanting to buy a home as the required income to qualify has roughly doubled from just a few years ago.”
Compared to one year ago, the national median single-family existing-home price grew 4.9% to $422,100. In the previous quarter, the year-over-year national median price increased 5%.
Among the major U.S. regions, the South registered the largest share of single-family existing-home sales (45.5%) in the second quarter, with year-over-year price appreciation of 2.3%. Prices also bounced 9.8% in the Northeast, 5.5% in the Midwest and 5.4% in the West.[i]
The top 10 metro areas with the largest year-over-year median price increases, which can be influenced by the types of homes sold during the quarter, all posted gains of at least 14.1%. Five of the markets were in the Northeast. Overall, those markets were Racine, Wis. (19.8%); Glens Falls, N.Y. (19.8%); El Paso, Texas (19.2%); Morristown, Tenn. (16.7%); Manchester-Nashua, N.H. (16.2%); Anaheim-Santa Ana-Irvine, Calif. (15.0%); New York-Jersey City-White Plains, N.Y.-N.J. (14.8%); Springfield, Ill. (14.8%); Dutchess County-Putnam County, N.Y. (14.2%); and Trenton, N.J. (14.1%).
Seven of the top 10 most expensive markets in the U.S. were in California. Overall, those markets were San Jose-Sunnyvale-Santa Clara, Calif. ($2,008,000; 11.6%); San Francisco-Oakland-Hayward, Calif. ($1,449,000; 8.5%); Anaheim-Santa Ana-Irvine, Calif. ($1,437,500; 15%); Urban Honolulu, Hawaii ($1,101,500; 3.8%); San Diego-Carlsbad, Calif. ($1,050,000; 11.4%); Salinas, Calif. ($1,035,700; 13.1%); Oxnard-Thousand Oaks-Ventura, Calif. ($927,900; 2.5%); San Luis Obispo-Paso Robles, Calif. ($895,300; 0.5%); Boulder, Colo. ($888,300; 2%); and Naples-Immokalee-Marco Island, Fla. ($867,000; 2%).
Nearly 10% of markets (22 of 223) experienced home price declines in the second quarter, up from 7% in the first quarter.
“Previously fast-gaining markets took a breather in the past quarter, including Nashville, Durham, Austin, and several Florida metro areas,” Yun said. “Conversely, some markets that experienced declines last year have roared back, such as San Francisco, Anaheim, and New York.”
Housing affordability worsened in the second quarter as mortgage rates increased. The monthly mortgage payment on a typical existing single-family home with a 20% down payment was $2,262, up 11.1% from the first quarter ($2,036) and 10.3% – or $212 – from one year ago. Families typically spent 26.5% of their income on mortgage payments, up from 24.2% in the previous quarter and 25.3% one year ago.
First-time buyers encountered limited inventory and rising home prices in the second quarter, resulting in deteriorated affordability conditions compared to the prior quarter. For a typical starter home valued at $358,800 with a 10% down payment loan, the monthly mortgage payment jumped to $2,218, up 11.1% from the previous quarter ($1,997). That was an increase of $207, or 10.3%, from one year ago ($2,011). First-time buyers typically spent 40% of their family income on mortgage payments, up from 36.5% in the prior quarter.
A family needed a qualifying income of at least $100,000 to afford a 10% down payment mortgage in 48% of markets, up from 40.7% in the previous quarter. Yet, a family needed a qualifying income of less than $50,000 to afford a home in 2.7% of markets, down from 4.5% in the prior quarter.
“Housing affordability will improve in upcoming months,” Yun said. “Mortgage rates have fallen measurably, and more supply is reaching the market. Therefore, the income required to buy a home will decrease.”
About the National Association of REALTORS®
The National Association of REALTORS® is America’s largest trade association, representing 1.5 million members involved in all aspects of the residential and commercial real estate industries. The term REALTOR® is a registered collective membership mark that identifies a real estate professional who is a member of the National Association of REALTORS® and subscribes to its strict Code of Ethics.
# # #
Data tables for MSA home prices (single-family and condo) are posted at https://www.nar.realtor/research-and-statistics/housing-statistics/metropolitan-median-area-prices-and-affordability. If insufficient data is reported for an MSA in a particular quarter, it is listed as N/A. For areas not covered in the tables, please contact the local association of REALTORS®.
NOTE: NAR releases quarterly median single-family price data for approximately 220 Metropolitan Statistical Areas (MSAs). In some cases, the MSA prices may not coincide with data released by state and local REALTOR® associations. Any discrepancy may be due to differences in geographic coverage, product mix, and timing. In the event of discrepancies, REALTORS® are advised that for business purposes, local data from their association may be more relevant.
1 Areas are generally metropolitan statistical areas as defined by the U.S. Office of Management and Budget. NAR adheres to the OMB definitions, although in some areas an exact match is not possible from the available data. A list of counties included in MSA definitions is available at: https://www.census.gov/geographies/reference-files/time-series/demo/metro-micro/delineation-files.html.
Regional median home prices are from a separate sampling that includes rural areas and portions of some smaller metros that are not included in this report; the regional percentage changes do not necessarily parallel changes in the larger metro areas. The only valid comparisons for median prices are with the same period a year earlier due to seasonality in buying patterns. Quarter-to-quarter comparisons do not compensate for seasonal changes, especially for the timing of family buying patterns.
Median price measurement reflects the types of homes that are selling during the quarter and can be skewed at times by changes in the sales mix. For example, changes in the level of distressed sales, which are heavily discounted, can vary notably in given markets and may affect percentage comparisons. Annual price measures generally smooth out any quarterly swings.
NAR began tracking of metropolitan area median single-family home prices in 1979; the metro area condo price series dates back to 1989.
The seasonally adjusted annual rate for a particular quarter represents what the total number of actual sales for a year would be if the relative sales pace for that quarter was maintained for four consecutive quarters. Total home sales include single-family, townhomes, condominiums and co-operative housing.